

Political Cycles: An Empirical Guide for Researchers and Analysts
Political cycles are recurring patterns in economic policy and outcomes that governments produce in response to electoral incentives and partisan preferences. The single most durable empirical finding: governments in many democracies expand fiscal and monetary policy before elections, and inflation tends to rise in the period immediately after, though the strength of that pattern depends heavily on institutional context.
Three findings anchor the literature:
- William Nordhaus’s 1975 paper established the canonical political business cycle (PBC) model, showing how vote-maximizing incumbents manipulate output and unemployment ahead of elections, creating predictable boom-bust rhythms tied to electoral calendars.
- Alberto Alesina and Nouriel Roubini’s landmark cross-country review found that political cycles and macroeconomic outcomes are more complex than the simple Nordhaus story: partisan ideology, rational expectations, and institutional design all modify the basic pattern.
- NBER/OECD cross-country tests largely reject the classic output-unemployment cycle but consistently find post-electoral inflation increases, a result that holds across 18 OECD economies over three decades.
The most important citation anchor for this article: Alesina, Roubini, and Cohen’s empirical synthesis across OECD countries remains the standard reference for anyone mapping how electoral timing, party orientation, and competition jointly shape unemployment, growth, inflation, and macro policy.
Key Takeaways
Post-electoral inflation increases are the most robust finding in political-cycle research, but nearly every other effect depends on institutional context, making conditional analysis the only credible approach.
| Point | Details |
|---|---|
| Post-electoral inflation is the robust finding | Cross-country OECD tests consistently find inflation rises after elections; the output cycle is far weaker. |
| Institutional context determines effect size | Central bank independence, fiscal rules, and electoral system type are the primary moderators of cycle strength. |
| Partisan effects concentrate at turnover | Ideological shifts in inflation and unemployment are most detectable in the first one to two years after a government change. |
| Subfaction dynamics complicate party-label models | Pew’s 2026 typology shows nine distinct U.S. voter groups; simple red/blue cycle models increasingly miss within-coalition policy shifts. |
| Identification quality separates credible findings | Placebo tests, pre-trend checks, and robustness to window length are the minimum standards for any political-cycle claim. |
Table of Contents
- What are the main theories behind political cycles?
- How did political-cycle research develop historically?
- What does the empirical evidence actually show?
- How do elections influence monetary policy and central-bank behavior?
- What are the causal channels linking elections to economic outcomes?
- How do researchers measure and identify political cycles?
- What does U.S.-specific evidence show about election cycles?
- How do political cycles affect asset prices and market behavior?
- What are the main criticisms and limitations of political-cycle research?
- An analyst’s checklist for assessing political-cycle claims
- How to weigh political-cycle evidence: an editorial perspective
- Sources
What are the main theories behind political cycles?
The political business cycle literature divides into three main theoretical families, each with a distinct causal story and a different empirical prediction. Understanding which model you are working with matters because the predictions diverge sharply once you move beyond the headline claim that elections affect policy.
Opportunistic models: Nordhaus and the vote-maximizing incumbent
The opportunistic model, formalized by Nordhaus in 1975, starts from a simple premise: incumbents want to win, voters reward good economic conditions, and governments have enough short-run control over output and unemployment to exploit that link. The prediction is a pre-electoral boom followed by a post-electoral correction. Crucially, the model assumes voters are myopic — they weight recent conditions more heavily than the full policy record. That assumption is what makes the manipulation worthwhile for the incumbent and what makes it empirically testable: you look for systematic output or unemployment improvements in the quarters before elections.
Partisan and rational partisan models: Alesina’s contribution
Alberto Alesina’s partisan model shifts the mechanism entirely. Instead of myopic voters, the story is ideological commitment: left-leaning governments genuinely prefer lower unemployment and higher inflation, while right-leaning governments prefer the reverse. The prediction is not a cycle tied to the electoral calendar but a shift at the moment of government turnover. A newly elected left government expands; a newly elected right government contracts. The rational partisan extension adds wage contracts and imperfect information: because workers sign nominal contracts before knowing the election outcome, the winning party can produce real effects in the short run even if everyone is forward-looking. Over time, as contracts adjust, the real effects fade and only the inflation or unemployment preference of the ruling party persists.
Long-cycle and social-cycle approaches
A third family operates at a much longer time horizon. These approaches, drawing on thinkers from Kondratiev to Schlesinger, argue that democratic societies oscillate between periods of activist government and periods of retrenchment over decades, not electoral windows. The mechanism is generational: cohorts that lived through a period of reform eventually tire of it, and the political coalition shifts. These models are harder to test rigorously because the cycles are long relative to available data, but they inform how analysts think about secular trends in regulation, taxation, and the size of government.
| Theoretical model | Core mechanism | Typical prediction | Time horizon | Empirical fit |
|---|---|---|---|---|
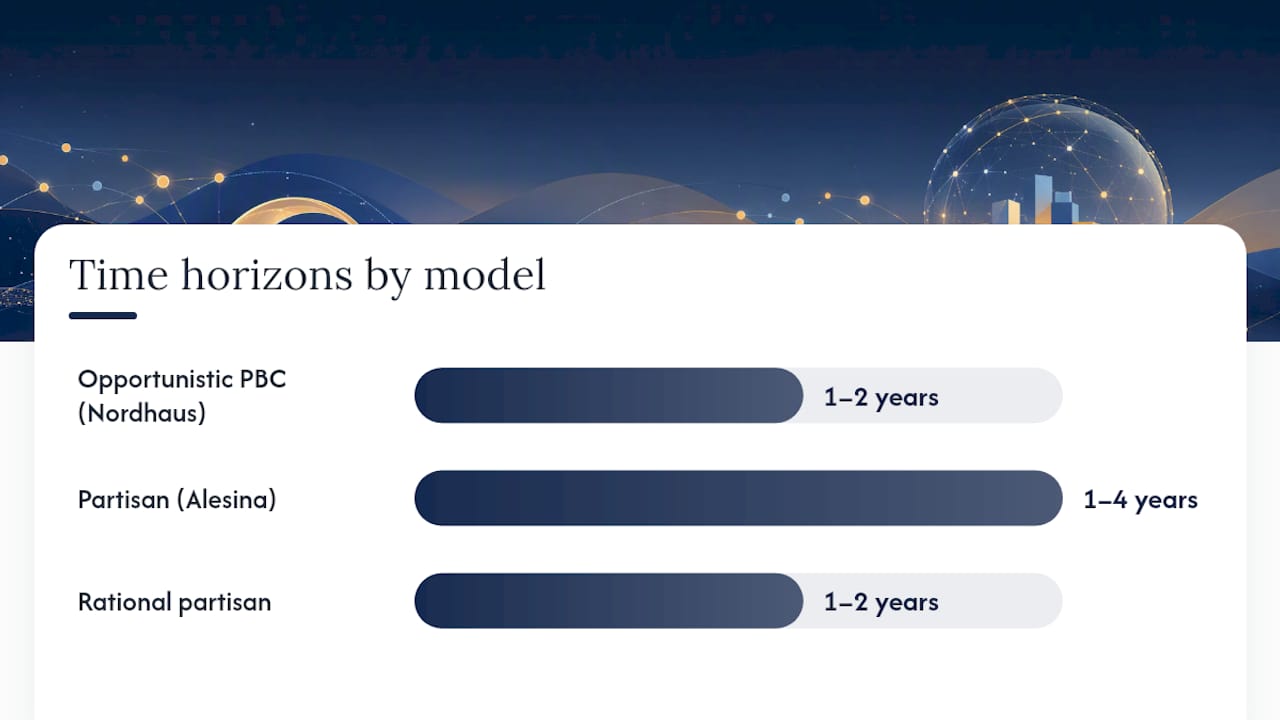
| Opportunistic PBC (Nordhaus) | Myopic voters; incumbents boost output pre-election | Pre-electoral expansion; post-electoral contraction | Electoral window (1–2 years) | Mixed; inflation rise more robust than output cycle |
| Partisan (Alesina) | Ideological preferences differ by party | Post-turnover shifts in inflation and unemployment | Medium-term (1–4 years) | Moderate support in OECD data |
| Rational partisan | Partisan preferences plus nominal rigidities | Short-run real effects at turnover; fade as contracts adjust | Short-to-medium (1–2 years) | Partial support; sensitive to institutional context |
| Long/social cycle | Generational coalition shifts | Decade-scale swings in government size and activism | 20 years | Descriptive; limited formal testing |
How did political-cycle research develop historically?
The intellectual lineage of political-cycle research stretches back well before Nordhaus, though the formal empirical program is largely a product of the 1970s and 1980s.
- Classical antecedents. Aristotle’s Politics observed that democracies tend toward redistributive pressures that destabilize property rights. Machiavelli noted the strategic use of public beneficence before critical political moments. These are normative and descriptive observations, not formal models, but they capture the core intuition that rulers time generosity to consolidate power.
- Early 20th-century cycle thinking. Michał Kalecki’s 1943 essay “Political Aspects of Full Employment” argued that capitalist governments would never sustain full employment because business interests would resist the political empowerment of labor. That is a partisan-style argument, made decades before Alesina formalized it.
- The Nordhaus moment (1975). William Nordhaus published “The Political Business Cycle” in the Review of Economic Studies, providing the first formal model with testable predictions. The paper arrived at a moment when stagflation had shaken confidence in technocratic macroeconomic management, making the idea that policy was politically distorted immediately plausible.
- The 1980s formalization wave. Alesina’s partisan model (1987), the rational partisan extension (1988), and the Rogoff-Sibert signaling model of electoral budget cycles all appeared within a few years of each other. This wave shifted the literature from a single opportunistic story to a richer set of competing hypotheses.
- The 1990s cross-country turn. With the spread of democracy and the availability of comparable OECD macro data, researchers could test these models across countries rather than relying on single-country time series. The NBER working paper by Alesina and Roubini covering 18 OECD economies exemplifies this shift.
Modern formal models resolved the classical claims by replacing normative intuitions with explicit utility functions, rational agents, and testable equilibrium conditions. The gain was precision and falsifiability. The cost was that the richness of historical and institutional context sometimes got stripped away, which is why the empirical literature has increasingly moved toward country-specific and institutional moderator analyses.
What does the empirical evidence actually show?
The empirical record on political cycles is genuinely mixed, and that heterogeneity is itself informative. Here is what the major studies find.
Annotated study summary
Nordhaus (1975): Using U.S. and cross-country data available in the early 1970s, Nordhaus documented patterns consistent with pre-electoral output expansions. The paper is foundational but predates modern identification strategies; later replications with better data and controls have produced weaker results for the output cycle specifically.
Alesina and Roubini (1992, NBER Working Paper 3478): Testing 18 OECD economies over roughly three decades, this study largely rejects the classic Nordhaus output-unemployment cycle but finds a consistent post-electoral inflation increase. The interpretation: pre-electoral expansionary policies show up in prices with a lag, not in real output, because rational agents partially anticipate the manipulation. The cross-country OECD evidence is the most cited empirical benchmark in the field.
Alesina, Roubini, and Cohen (book, MIT Press): The full book-length treatment synthesizes theoretical models and cross-country evidence and reaches a key conclusion: the U.S. is not exceptional. Political-economic cycle relationships in America resemble those in other democracies, with complex interactions among electoral law, timing, and macro policies.
Martinez (Richmond Fed Working Paper, 2005): This Richmond Fed working paper formalizes how election proximity affects policy choices, providing a theoretical bridge between the opportunistic and signaling literatures. It is widely cited for its clean model of how the distance to the next election shapes the incumbent’s policy calculus.
Pástor and Veronesi (Journal of Political Economy): This paper develops a model in which political cycles and stock returns are linked through time-varying risk aversion and political-sectoral labor choices. The finding: political conditions affect the equity risk premium, producing return patterns that correlate with electoral cycles under certain institutional conditions.
Common empirical regularities
- Pre-electoral fiscal expansion is the most consistently documented pattern, particularly in countries with weaker institutional constraints on executive spending.
- Post-electoral inflation increases are more robust than output cycles across OECD data, consistent with the rational-partisan and signaling models.
- Partisan effects on inflation and unemployment are detectable at government turnover, especially in the first one to two years of a new administration.
- Effects are stronger in presidential systems, in countries with less independent central banks, and in developing economies with weaker fiscal rules.
Evidence strength by outcome
The evidence is robust for post-electoral inflation increases in OECD data, moderate for partisan turnover effects on inflation and unemployment, mixed for pre-electoral output booms (depends heavily on the country and time period), and limited for the full Nordhaus boom-bust cycle in modern developed economies with independent central banks.
| Study | Data span | Main finding | Geographic scope | Identification approach |
|---|---|---|---|---|
| Nordhaus (1975) | Pre-1975 U.S. and cross-country | Pre-electoral output expansion | U.S. and select democracies | Time-series pattern matching |
| Alesina & Roubini (NBER 3478) | ~1970–2000, 18 OECD | Output cycle rejected; post-election inflation rises | OECD | Cross-country fixed effects, event windows |
| Alesina, Roubini & Cohen (MIT Press) | Multi-decade OECD | U.S. not exceptional; complex institutional interactions | OECD | Comparative empirical synthesis |
| Martinez (Richmond Fed, 2005) | Theoretical | Election proximity shapes policy calculus | General (theoretical) | Formal model with policy implications |
| Pástor & Veronesi (JPE) | Multi-decade U.S. | Political conditions affect equity risk premium | U.S. | Asset pricing model with political state variable |
How do elections influence monetary policy and central-bank behavior?
The political monetary cycle is a distinct but related phenomenon: electoral timing can influence interest rate decisions, money supply growth, and central bank communication, not just fiscal policy. The mechanism runs through two channels. First, an elected government may pressure a central bank to keep rates low ahead of an election, supporting growth and employment at the cost of future inflation. Second, even without direct pressure, a central bank whose leadership is appointed by the executive may internalize political preferences, particularly when appointments cluster near election cycles.
Empirical work on this question has grown substantially since 2010. Studies covering both developed and developing countries find evidence that elections influence central bank behavior, but the effects are conditional on institutional design. Three institutional conditions determine whether a monetary cycle is likely:
- Central bank independence. Countries with legally independent central banks and fixed-term governors show weaker monetary cycles. The U.S. Federal Reserve’s structure, with staggered terms and statutory independence, provides meaningful insulation, though it does not eliminate political pressure entirely.
- Appointment timing. When a governor’s term expires close to an election, the appointing government has leverage over the successor’s preferences. Researchers test this by checking whether policy changes cluster around appointment windows.
- Legal constraints on money financing. Countries where the central bank is prohibited from directly financing government deficits show weaker monetary cycles because the fiscal-monetary transmission channel is blocked.
A concrete illustration of the pre-electoral mechanism: a government facing an election in six months pushes for accommodative monetary policy to support employment. The central bank, whether through direct pressure or shared preferences, holds rates lower than the inflation outlook would justify. Output and employment improve modestly before the vote. After the election, the inflationary pressure from the earlier accommodation becomes visible, and the central bank tightens. The result is the post-electoral inflation pattern that Alesina and Roubini document in OECD data. For a deeper look at how this political-inflation link plays out in practice, the Joshthinks analysis of inflation as a political issue covers the voter-facing dimension of the same mechanism.
Pro Tip: When testing for political monetary cycles, check whether the effect concentrates in the quarters when a central bank governor’s term overlaps with an electoral window. If the cycle disappears when you exclude those overlapping periods, the appointment channel is likely doing most of the work.
What are the causal channels linking elections to economic outcomes?
The theoretical models predict cycles, but the channels through which electoral incentives translate into observable outcomes are distinct and worth separating, because each channel has a different empirical signature and a different policy implication.
Fiscal stimulus. The most direct channel: governments increase spending or cut taxes ahead of elections. The empirical test is straightforward — look for pre-electoral increases in the primary deficit, infrastructure spending, or transfer payments. The challenge is separating electoral timing from automatic stabilizers and genuine economic need.
Monetary signaling. Even without direct central bank manipulation, a government can signal its preferred policy stance through appointments, public statements, and budget projections. Markets and wage-setters respond to these signals, producing real effects before any actual policy change. This is the channel the Martinez Richmond Fed model formalizes.
Regulatory forbearance. Governments sometimes delay enforcement actions, postpone regulatory rulings, or slow the implementation of costly rules in the run-up to an election. This is harder to measure than fiscal variables but shows up in studies of financial regulation, environmental enforcement, and antitrust timing.
Appointments and personnel. Cabinet reshuffles, agency head appointments, and judicial nominations all cluster around electoral cycles. Each appointment can shift the policy stance of an institution for years beyond the electoral window. The systemic incentives behind political appointments and how they can distort policy are worth understanding alongside the formal cycle literature.
Electoral timing endogeneity. In parliamentary systems, the government often chooses when to call an election. This creates a selection problem: elections are more likely to be called when economic conditions are favorable, which makes it look like the economy improves before elections even when no manipulation is occurring. Researchers address this with fixed-schedule elections as natural experiments or by using instrumental variables for election timing.
Pro Tip: To diagnose which channel is operating in a specific dataset, run separate regressions for fiscal balance, central bank rate changes, regulatory action counts, and appointment frequency on an election-proximity indicator. The channel with the strongest and most precisely estimated coefficient is the primary transmission mechanism for that country and period.
How do researchers measure and identify political cycles?
Credible identification is the central methodological challenge in this literature. The core problem: elections are not random events, and the economy is not stationary, so naive before-after comparisons are almost always confounded.
Common empirical approaches
- Event-study windows. Define a window of, say, four to eight quarters around each election and test whether the outcome variable (deficit, inflation, output growth) behaves differently inside the window than outside. The FEC’s legally defined election-cycle windows matter here: for U.S. federal offices, a cycle begins the day after the previous general election and ends on the day of the next general election for that seat, with House cycles running two years, Senate six, and presidential four. Aligning empirical windows with these legal definitions avoids measurement error in the treatment variable.
- Fixed effects. Country and time fixed effects absorb time-invariant country characteristics and common global shocks. This is the standard approach in cross-country panels.
- Difference-in-differences. Compare countries or states with elections in a given year to those without, using the non-election group as the counterfactual. Requires a parallel-trends assumption that is worth testing explicitly.
- Instrumental variables. Use constitutionally fixed election schedules as instruments for actual election timing in countries where early elections are possible. The instrument is valid if the constitutional schedule affects outcomes only through the election itself.
- Regression discontinuity. In close elections, the winner is essentially random near the threshold, allowing clean causal inference about the effect of party identity on subsequent policy. This design is increasingly popular in the partisan-effects literature.
Checklist for credible identification
- Test for pre-trends: does the outcome variable start moving before the event window opens, suggesting anticipation or confounding?
- Run placebo windows: do the same patterns appear in non-election years? If yes, the result is likely spurious.
- Check robustness to window length: does the finding hold for four-quarter, six-quarter, and eight-quarter windows, or is it sensitive to the exact cutoff?
- Report heterogeneity: does the effect differ by institutional setting (central bank independence, electoral system, fiscal rules)?
- Replicate on a holdout sample or a different country group.
Key data sources
State-level election cycle definitions vary across the U.S., a detail the NCSL documents and that matters when researchers aggregate campaign-driven fiscal measures at the sub-federal level. For macro variables, the standard repositories are FRED (Federal Reserve Bank of St. Louis), the IMF World Economic Outlook database, the World Bank’s World Development Indicators, and the OECD Economic Outlook. For political variables, the Database of Political Institutions (DPI) and the Comparative Political Data Set (CPDS) are the most widely used. For U.S. campaign finance data, the FEC’s bulk data files are the authoritative source.
What does U.S.-specific evidence show about election cycles?
The U.S. offers a rich laboratory for political-cycle research because of its fixed electoral calendar, divided government, Federal Reserve independence, and the sheer volume of available data. The broad finding from Alesina, Roubini, and Cohen is that U.S. patterns are not exceptional: the same theoretical mechanisms operate here as in other OECD democracies, though institutional moderators shape the magnitude.
Three illustrative episodes
The 1972 election and Nixon’s Fed pressure. The most cited U.S. case of a political monetary cycle: the Nixon administration pressured Federal Reserve Chairman Arthur Burns to keep monetary policy accommodative ahead of the 1972 presidential election. The result was strong pre-electoral growth followed by the inflation surge of 1973–1974. This episode is frequently cited as the textbook example of what central bank independence is designed to prevent.
Reagan-era fiscal expansion (1981–1984). The 1981 tax cuts and defense buildup produced a large fiscal expansion that contributed to the 1983–1984 recovery, timed favorably for the 1984 election. Whether this was deliberate electoral timing or ideological policy is precisely the partisan-vs-opportunistic debate in miniature.
Pre-election fiscal packages in the 2000s and 2020s. Stimulus checks and tax rebates in 2001, 2008, and 2020–2021 all occurred near electoral windows, though in each case the stated justification was economic stabilization rather than electoral strategy. Separating the two motivations is exactly the identification challenge the literature grapples with.
U.S.-specific institutional moderators
- Federal Reserve independence. The Fed’s statutory independence and the staggered terms of its Board of Governors reduce but do not eliminate political influence on monetary policy.
- Separation of powers. Divided government (different parties controlling Congress and the White House) constrains fiscal manipulation because the opposing party has both the incentive and the institutional power to block pre-electoral spending.
- Staggered Senate terms. Because only one-third of Senate seats are contested in any given election year, the Senate is structurally less susceptible to short-term electoral pressures than the House.
- State vs. federal cycles. State-level fiscal cycles can diverge from federal ones because governors face different electoral calendars, balanced-budget requirements, and tax bases. Researchers studying U.S. subnational data must account for these differences.
Modern U.S. political dynamics add another layer of complexity. Pew Research’s 2026 political typology divides the U.S. public into nine distinct groups, with record-high independent identification, implying that simple party-label models of political cycles miss the subfaction dynamics that increasingly drive policy outcomes. Navigator Research’s mid-2026 surveys reinforce this: significant within-party divisions mean that the winning party’s policy stance is less predictable from its label alone than it was in earlier decades. For analysts, this means tracking subfaction composition of governing coalitions, not just party control.
How do political cycles affect asset prices and market behavior?
Markets price political risk, and the political business cycle literature has a direct translation into asset pricing. The key insight from Pástor and Veronesi’s work in the Journal of Political Economy: political conditions affect stock returns through time-varying risk aversion and the sectoral labor choices that different political regimes favor. The equity risk premium is not constant across the electoral cycle; it tends to be higher under conditions of political uncertainty and lower once an election resolves that uncertainty.
What the evidence shows for specific asset classes
Equities. Stock returns often tend to be higher in the second half of a presidential term than the first, based on observed patterns in U.S. data. The mechanism is uncertainty resolution: the first half of a term is when policy uncertainty is highest (new administration, new priorities), and the second half is when the policy path becomes clearer. This is not a reliable trading rule, but it is a systematic pattern worth understanding.
Bonds and yields. Pre-electoral fiscal expansion tends to widen deficits, which puts upward pressure on long-term yields. Post-electoral inflation increases, documented in OECD data, also push yields higher after elections. Bond markets therefore tend to price in political-cycle risk through the term premium.
Volatility. Implied volatility (measured by instruments like the VIX) typically rises in the weeks before a major election and falls sharply after the result is known, regardless of which party wins. The uncertainty itself is the priced risk, not the partisan outcome.
Sector-level effects to monitor
- Defense and aerospace: spending tends to increase under right-leaning governments and during periods of geopolitical tension that often accompany political transitions.
- Infrastructure and construction: left-leaning governments and pre-electoral spending packages tend to favor public investment, benefiting these sectors.
- Regulated utilities and healthcare: sectors subject to heavy regulation are sensitive to regulatory-cycle effects; a change in administration can shift the expected regulatory burden significantly.
- Consumer discretionary: responds to pre-electoral transfer payments and tax cuts that boost household disposable income.
For readers who want to translate political-cycle signals into specific market instruments, Joshthinks’s guide to financial futures covers how futures markets price macro and political risk across asset classes.
Pro Tip: To distinguish a political-cycle-driven market move from a concurrent macro shock, run a regression of the return or yield change on both the election-proximity indicator and standard macro controls (GDP surprise, inflation surprise, Fed funds rate change). If the political variable loses significance once macro controls are included, the move is more likely macro-driven. If it remains significant, the political channel is contributing independently.
What are the main criticisms and limitations of political-cycle research?
The political business cycle literature has accumulated a substantial set of methodological critiques, and honest engagement with them is what separates credible analysis from pattern-matching.
Core methodological problems
Endogeneity of election timing. In parliamentary systems, the government chooses the election date. This means elections are more likely when the economy is already doing well, creating a spurious correlation between pre-electoral conditions and electoral timing. Studies that treat election dates as exogenous in parliamentary systems are potentially biased.
Measurement error in the treatment variable. What counts as “the electoral window”? A two-quarter window, a four-quarter window, and an eight-quarter window can produce very different results. The FEC’s legal definition of election cycles for campaign finance purposes is precise, but empirical researchers often use different windows without justification, making cross-study comparisons difficult.
Omitted variables. Global business cycles, commodity price shocks, and financial crises all affect macro outcomes and may cluster near elections by coincidence. Studies that do not adequately control for these confounders will overstate political-cycle effects.
Small samples. Most countries have had only 10–20 elections in the post-WWII period. With that many observations, it is easy to find patterns that do not replicate out of sample.
Where effects are weakest or absent
- Countries with strong fiscal rules (constitutional debt brakes, independent fiscal councils) show weaker pre-electoral fiscal cycles because the rules constrain the manipulation.
- Countries with highly independent central banks show weaker monetary cycles.
- Proportional representation systems with coalition governments show weaker partisan effects because the governing coalition averages across multiple parties’ preferences.
- Developing economies with weak institutions sometimes show stronger cycles, but the identification challenges are also more severe in those settings.
Open empirical challenges
The biggest unresolved question is heterogeneity: why do political cycles appear strongly in some countries and time periods and weakly or not at all in others? The answer almost certainly lies in institutional moderators, but the literature has not yet produced a unified framework for predicting which institutions matter most and by how much. A related challenge is the shift in coalition dynamics documented by Pew and Navigator: as within-party factions increasingly drive policy, the simple party-label models that underpin most partisan-cycle tests may be losing explanatory power. Analysts who rely on trade deficit and macro feedback loops as part of their political-cycle framework should account for this subfaction complexity.
An analyst’s checklist for assessing political-cycle claims
The empirical record supports a clear, bounded verdict: political cycles are real in the sense that electoral timing and partisan identity systematically influence fiscal and monetary policy choices in many democracies, but the effects are conditional, heterogeneous, and often smaller than the theoretical models predict. Post-electoral inflation increases are the most robust finding. Pre-electoral output booms are the least robust. Partisan effects at government turnover are in between.
When political cycles matter most
- Fixed electoral calendars (reduces endogeneity of timing)
- Weak central bank independence (opens the monetary channel)
- Presidential or majoritarian systems (fewer veto players, easier fiscal manipulation)
- Developing economies with limited fiscal rules
- First term of a new government (partisan effects are strongest early)
Analyst checklist for evaluating a political-cycle claim
- Is the election timing exogenous, or could the government have called the election when conditions were favorable?
- Is the event window defined before looking at the data, or was it chosen to fit the result?
- Are standard macro controls included (global growth, commodity prices, financial conditions)?
- Is the finding robust to alternative window lengths and control sets?
- Does the effect differ by institutional setting in a theoretically predicted direction?
- Is the sample large enough to support the claimed precision?
- Has the result been replicated on a different country group or time period?
Research gaps worth pursuing
- Better identification of the appointment channel: how much of the monetary cycle runs through governor appointments versus direct pressure?
- Subfaction-level analysis: do within-party ideological shifts produce detectable policy cycles independent of party turnover?
- High-frequency market data: can intraday or weekly data identify political-cycle signals that quarterly macro data misses?
- Developing-country heterogeneity: what institutional thresholds separate countries with strong cycles from those with weak ones?
Pro Tip: The single most useful robustness check for any political-cycle paper is a placebo test using non-election years as pseudo-event windows. If the same pattern appears in non-election years, the result is almost certainly spurious. Require this check before accepting any political-cycle finding as credible.
How to weigh political-cycle evidence: an editorial perspective
The political business cycle literature is one of the most intellectually honest fields in political economy, precisely because it has spent decades trying to falsify its own central claim. The Nordhaus model is elegant and intuitive, but the empirical record has forced repeated revisions: the output cycle is weaker than predicted, the inflation cycle is more robust, and institutional context explains more of the variance than the original theory anticipated.
What strikes me most about this literature is the gap between its academic nuance and how political-cycle claims get used in practice. Analysts and journalists routinely invoke “the political business cycle” as if it were a reliable, universal mechanism, when the actual evidence says it is conditional, heterogeneous, and sensitive to measurement choices. The post-electoral inflation finding is the one result that has held up consistently across countries and methods. Everything else requires an institutional qualifier.
For students, the best entry point is still Alesina, Roubini, and Cohen’s MIT Press book: it covers theory and evidence in a single volume and forces you to engage with the identification challenges from the start. For analysts, Pástor and Veronesi’s asset pricing work is the most practically useful, because it translates the political-cycle mechanism into a risk premium framework that connects directly to portfolio decisions. For journalists, the Pew 2026 typology is the most important recent document: the nine-group fragmentation of the U.S. electorate means that “the party in power” is an increasingly poor predictor of actual policy direction, which should make anyone cautious about simple partisan-cycle narratives.
The field’s open frontier is subfaction dynamics. As Pew’s 2026 typology shows, the U.S. electorate has fragmented well beyond a two-party model. Political-cycle research built on party labels alone is going to miss the within-coalition shifts that increasingly determine whether a government actually delivers the policy its label predicts. That is where the next generation of empirical work needs to go.
Sources
The following primary sources and data repositories are the standard starting points for anyone working on or reading political-cycle research.
Primary literature
- Political Cycles and the Macroeconomy
- Political Cycles and Stock Returns
- FEC | Tips | Election cycles and aggregation
Data repositories and institutional sources
For readers interested in how local media coverage shapes the public perception of political-cycle policy moves, the Central Georgian’s guide to local election coverage offers useful context on how electoral-timing signals reach voters through local journalism. Understanding how newsrooms decide what to cover is also relevant for analysts who use media sentiment as a proxy variable for political-cycle intensity.


