

A Biblical Perspective on Government Taxation
The Bible offers principles for taxation, not a modern tax code. Romans 13:1–7 commands Christians to pay taxes to governing authorities, and Matthew 22:21 draws the famous line: “Give to Caesar what is Caesar’s, and to God what is God’s.” Neither passage specifies a rate, a structure, or a preferred fiscal policy. What Scripture does supply are moral constraints: taxation should be proportional, non-exploitative, and oriented toward the common good. The U.S. Conference of Catholic Bishops (USCCB) and scholars like Brian Baugus at Regent University both affirm this reading. For American readers, the practical implication is direct: use these biblical principles to evaluate tax policy on moral grounds, not to demand a single scriptural rate.
Table of Contents
- What does the Bible actually say about government taxation?
- How major traditions and scholars interpret these texts
- What does Scripture say about the ethics of paying taxes and using loopholes?
- How biblical redistribution principles inform modern welfare debates
- How do biblical principles translate into U.S. tax policy questions?
- How should Christians respond to “taxation is theft”?
- A practical framework for Christian civic engagement on taxes
- How this article was built and where to read further
- Key Takeaways
What does the Bible actually say about government taxation?
The two passages that anchor every serious Christian discussion of taxes are Matthew 22:15–22 and Romans 13:1–7 are vividly interpreted and explored in Saints, Scripture & Christian Art – Divine Prints, which offers rich visual and cultural context for these pivotal passages. In Matthew, Jesus is handed a denarius and asked whether Jews should pay the Roman imperial tax. His answer sidesteps the trap: the coin bears Caesar’s image, so render it to Caesar. In Romans, Paul is explicit: “Give everyone what you owe him: If you owe taxes, pay taxes” (Romans 13:7). Both texts treat civic taxation as a legitimate obligation, not an optional courtesy.
Beyond those anchors, the Old Testament adds texture:
- Deuteronomy 14:22–29 and Leviticus 27:30–33 establish the tithe as a religious obligation funding the Levitical priesthood and care for the poor, not a template for state income tax.
- Leviticus 19:9–10 and Deuteronomy 24:19–22 prescribe gleaning laws: landowners must leave field edges unharvested for the poor and the stranger.
- Leviticus 25 introduces the Jubilee, a periodic reset of land and debt designed to prevent permanent wealth concentration.
- Amos 5:11–12 denounces rulers who tax grain from the poor and take bribes, framing exploitative levies as a justice violation.
- The temple tax (Matthew 17:24–27) shows a separate religious levy distinct from Roman civic taxes, reinforcing that the two systems operated on different authority bases.
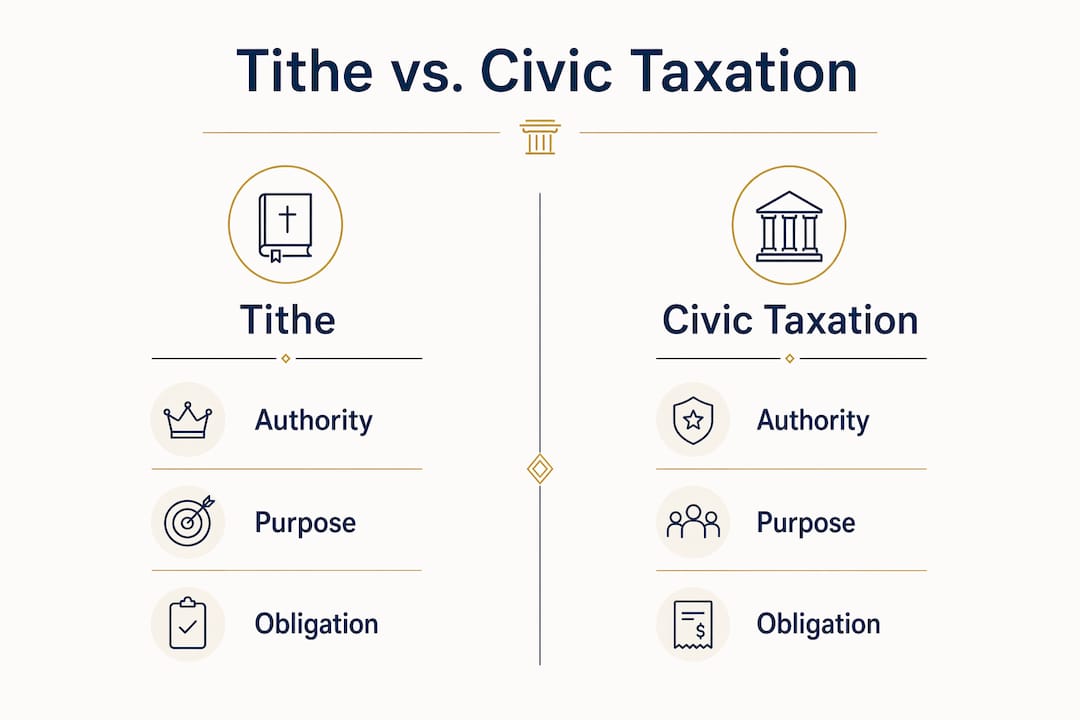
Tithe vs. civic taxation: a direct comparison
| Dimension | Tithe (religious obligation) | Civic taxation |
|---|---|---|
| Authority | God, through Mosaic covenant | Governing civil authority |
| Purpose | Ministry support, care for poor | Public order, common goods |
| Scope | Covenant community of Israel | All residents under civil rule |
| Rate | Roughly 10% of agricultural produce | Varies; no scriptural mandate |
| Moral basis | Worship and covenant faithfulness | Justice, order, common good |
The tithe’s redistributive function was real, but it operated inside a theocratic covenant structure that no modern nation replicates. Reading it as a scriptural argument for a 10% flat income tax collapses a crucial distinction.
How major traditions and scholars interpret these texts
Catholic social teaching, as articulated by the USCCB and the Catholic Bishops’ Conference, treats taxation as lawful but bounded. The state has genuine authority to levy taxes for the common good, but that authority is not unlimited. Exploitative taxes that crush the poor or enrich rulers at the expense of justice violate the same moral order that legitimizes taxation in the first place. Amos is not background noise in this tradition; it is a live warning.
Protestant scholarship covers more ground. Brian Baugus at Regent University argues that Scripture implies principles of simplicity and proportionality and that modern tax complexity should be evaluated against those standards. Mainline Protestants tend to emphasize the state’s positive role in redistribution. Evangelical readers often stress individual stewardship and limited government. Anabaptist traditions read “render unto Caesar” as a boundary-setting act: Jesus is not endorsing Roman authority so much as limiting it by insisting God’s domain is not Caesar’s.
Dr. Robert G. Kennedy’s contribution cuts across these traditions with a sharp ethical point:
That distinction between legal and moral permissibility is where most contemporary Christian tax ethics gets interesting, and where Kennedy’s work is most useful.
Michael Bird’s survey of interpretive options notes that “render unto Caesar” has been read as an endorsement of state authority, a two-kingdoms framework, and a subversive act of boundary-setting. All three readings have serious theological defenders. The honest answer is that the text supports a range of conclusions about the scope of state power, which is precisely why biblical economic frameworks matter for interpreting it carefully.
What does Scripture say about the ethics of paying taxes and using loopholes?
Christians should pay lawfully imposed taxes. That is the plain reading of Romans 13 and Matthew 22, and it holds even when the government is not virtuous. Paul wrote Romans under Nero.
The harder question is loopholes. GotQuestions.org captures the mainstream Protestant position clearly: legal tax deductions are permissible; illegal or dishonest evasion is not. The line between legitimate planning and dishonest avoidance is not always obvious, though.
Consider two scenarios. A taxpayer claims the mortgage interest deduction Congress explicitly created. That is straightforward legal planning. A taxpayer uses a paper transaction with no economic substance to manufacture a loss, technically within the letter of the code but designed to deceive. Kennedy’s framework says the second scenario fails the honesty test even if no law is technically broken.
An ethical checklist for evaluating any tax strategy:
- Does this strategy rely on accurate representation of facts, or does it require misrepresentation?
- Was the tax provision I am using designed for my situation, or am I exploiting an unintended gap?
- Would I be comfortable if this strategy were fully transparent to my community?
- Does this planning reduce my ability to give generously or support public goods I benefit from?
- Am I motivated by legitimate stewardship, or by a desire to avoid obligations I genuinely owe?
Pro Tip: When evaluating a tax strategy, apply the transparency test: if full disclosure to your church, your employer, and the IRS would make you uncomfortable, that discomfort is a moral signal worth taking seriously.
How biblical redistribution principles inform modern welfare debates
Scripture’s redistribution mechanisms were structural, not merely charitable. Gleaning laws did not ask landowners to feel generous; they required leaving food accessible. Jubilee did not suggest debt forgiveness; it mandated it. Amos did not politely request fair treatment of the poor; he announced divine judgment on rulers who extracted wealth from them. These are biblical examples of resource redistribution built into the social architecture of ancient Israel.
What do those patterns imply for modern policy?
- Relief should be targeted and dignity-preserving, not humiliating or bureaucratically punitive.
- The family and the local community carry primary responsibility; the state steps in when those structures fail, not as a first resort.
- Structural mechanisms that prevent permanent poverty traps (debt relief, asset-building programs) align more closely with Jubilee logic than one-time cash transfers.
- Prophetic warnings about exploitative levies apply equally to regressive taxes that fall hardest on low-income households.
A concrete example: the Earned Income Tax Credit (EITC) functions as a wage subsidy for low-income workers. Read through a biblical lens, it resembles a gleaning mechanism: it leaves more income in the hands of those who work but earn little, without humiliating them. That does not make it scripturally mandated, but it fits the pattern of dignity-preserving relief better than a policy that simply extracts from the poor to fund unrelated priorities.
How do biblical principles translate into U.S. tax policy questions?
Biblical principles do not prescribe a tax rate, but they do supply a moral filter for evaluating policy proposals. The question is not “What would Moses charge?” but “Does this policy create undue hardship, favor narrow interests, or undermine the common good?”
Four principles map directly onto U.S. policy debates:
| Biblical principle | Policy question it raises |
|---|---|
| Proportionality | Does the tax burden fall roughly in proportion to ability to pay? |
| Non-exploitation | Does the policy extract disproportionately from low-income households? |
| Simplicity | Does complexity primarily serve powerful interests over ordinary taxpayers? |
| Subsidiarity | Does the tax structure respect the roles of family, church, and local community? |
Policy trade-offs worth examining through this lens:
- Progressive vs. proportional structures: A flat tax is proportional in rate but not necessarily in burden; a progressive structure attempts proportionality in burden. Both have biblical defenders.
- Tax expenditures: The U.S. tax code contains hundreds of deductions and credits. Many disproportionately benefit higher-income filers. The question of whether that constitutes a policy favoring narrow interests over the common good is a legitimate biblical concern, not merely a partisan one. Joshthinks explores how political corruption shapes tax policy in ways that compound this problem.
- Transparency: A tax system so complex that ordinary citizens cannot understand their obligations arguably fails the simplicity standard Scripture implies.
How should Christians respond to “taxation is theft”?
Three common arguments deserve direct responses.
1. “Taxation is theft.”
Romans 13 frames the state as an agent of God’s common grace for order and justice. Mainstream biblical scholarship does not support the blanket theft claim. A tax imposed by lawful authority for public goods is categorically different from coercive private taking. The argument has rhetorical force but poor scriptural grounding.
2. “The tithe proves God’s preferred tax rate is 10%.”
The tithe was a covenant religious obligation within ancient Israel’s theocratic structure, not a template for modern state income tax. Scholars at Regent University are explicit: equating the tithe with a state tax rate misreads both its purpose and its authority. For more on this misreading, see Joshthinks’s analysis of common biblical misinterpretations about wealth.
3. “I can refuse to pay taxes I morally disagree with.”
TaxNotes analysis draws the right distinction: moral disagreement with government spending does not remove the legal or moral duty to pay taxes imposed by lawful authority. Refusal is narrowly justified only when the state compels sinful action. Disagreeing with how revenue is spent does not meet that threshold.
A practical framework for Christian civic engagement on taxes
Christians navigating taxes faithfully need two things: clarity about personal conduct and a framework for civic action.
Personal conduct checklist:
- Pay what is legally owed, fully and on time.
- Use legal deductions and credits without guilt; they are part of the system.
- Reject dishonest evasion, even when detection is unlikely.
- Give generously from after-tax income; stewardship does not end at the tax return.
- Maintain transparency in financial dealings.
Civic advocacy checklist:
- Advocate for tax simplicity; complexity disproportionately burdens those without accountants.
- Oppose policies that extract from low-income households to subsidize narrow interests.
- Insist on transparency in how tax revenue is spent.
- Partner with faith-based organizations that deliver targeted, dignity-preserving relief.
- Engage elected representatives on tax policy with specific, principled arguments.
Pro Tip: Contact your congressional representative’s office with a specific policy concern (e.g., EITC expansion, tax code simplification) rather than a general complaint. Staffers track constituent contacts by issue, and specificity gets logged.
How this article was built and where to read further
This article draws on primary scriptural texts (Matthew 22, Romans 13, Leviticus, Deuteronomy, Amos), official church teaching (USCCB and Catholic Bishops’ Conference documents), peer-reviewed and institutional scholarship (Regent University’s Center for Christian Thought & Action, Dr. Robert G. Kennedy’s work), and policy analysis (TaxNotes). The hermeneutic approach is contextual and historical: passages are read in their original setting before application to modern questions, and no single text is treated as a complete policy prescription.
| Source | Note |
|---|---|
| Matthew 22:15–22; Romans 13:1–7 | Primary New Testament texts on civic tax obligations |
| Catholic Bishops’ Conference, Chapter Three | Canonical Catholic treatment of taxation and limits of authority |
| Regent University / Brian Baugus | Protestant scholarly argument for principles over prescribed rates |
| Dr. Robert G. Kennedy via The Imaginative Conservative | Honesty standard and limits of legal-but-dishonest avoidance |
| Bible Gateway — Matthew 22 | Primary text reference for the coin/Caesar episode |
| Michael Bird via Logos | Survey of interpretive options for “render unto Caesar” |
| Joshthinks — Biblical Economic Frameworks | Framework guide for applying theological-economic models |
| Joshthinks — Economic Justice Guide | Connects biblical justice standards to modern public policy |
This article is theological and ethical analysis, not legal or tax advice. For questions about your specific tax situation, consult a qualified tax professional or the IRS directly.
Key Takeaways
Scripture supplies moral constraints for taxation, not a prescribed rate: proportionality, non-exploitation, and orientation toward the common good are the operative biblical standards for evaluating any tax policy.
| Point | Details |
|---|---|
| Principles, not a tax code | Romans 13 and Matthew 22 establish duty to pay taxes; neither specifies a rate or structure. |
| Tithe ≠ state tax rate | The tithe served a covenant religious function distinct from civic taxation; equating them misreads both. |
| Honesty governs loopholes | Legal permissibility does not equal moral permissibility; dishonest avoidance fails the biblical honesty standard. |
| Redistribution has biblical roots | Gleaning laws, Jubilee, and prophetic warnings about exploitation all support dignity-preserving relief structures. |
| Dissent through advocacy, not refusal | Moral disagreement with spending does not justify non-payment; Scripture channels dissent through voice and civic engagement. |


