

Why the Cold War Shaped Global Finance: A Political-Economy Guide
The Cold War remade global finance by converting national security priorities into permanent fiscal, monetary, and institutional practices. What began as a geopolitical contest between Washington and Moscow produced the dollar’s global dominance, the IMF, the World Bank, offshore Eurodollar markets, and a sanctions toolkit that still governs trade today. Understanding why the Cold War shaped finance means tracing how security decisions became economic architecture.
The main mechanisms were four: institution-building (Bretton Woods, Marshall Plan, GATT), fiscal normalization (deficit spending and creative budget accounting), monetary engineering (Exchange Stabilization Fund, Federal Reserve swap lines, IMF credits), and economic statecraft (sanctions, aid, covert influence). Each one left structural marks that outlasted the conflict itself.
Key Takeaways
The Cold War converted national security priorities into permanent financial institutions, fiscal norms, and monetary tools that still govern the global economy in 2026.
| Point | Details |
|---|---|
| Institutions were strategic | Bretton Woods, IMF, World Bank, and GATT served both reconstruction and U.S. containment objectives simultaneously. |
| Deficits became normalized | Cold War defense commitments legitimized permanent deficit spending and creative budget accounting in U.S. fiscal practice. |
| Nixon shock ended the gold standard | Balance-of-payments pressure from Vietnam War spending forced Nixon to suspend dollar-gold convertibility in 1971. |
| Eurodollars created systemic risk | Soviet-seeded offshore dollar markets grew unregulated, requiring Fed swap lines approaching $580–600 billion in 2008 to stabilize. |
| Legacies govern finance today | Dollar dominance, sanctions regimes, Fed swap lines, and SDRs are all Cold War infrastructure still in active use. |
| Joshthinks connects history to markets | Joshthinks’ political-economy analysis ties Cold War financial origins to present-day dollar risk, pension exposure, and market mechanics. |
Table of Contents
- How Cold War priorities translated into financial change
- How Bretton Woods, the IMF, the World Bank, the Marshall Plan, and GATT structured international finance
- How Cold War strategy changed U.S. and global fiscal and monetary practice
- How aid, sanctions, and covert influence reshaped trade and markets
- How banking, capital mobility, and offshore dollar markets developed through the Cold War
- Key Cold War finance turning points from 1944 to 1991
- Why Cold War financial legacies still matter today
- A perspective on political economy and practical finance
- Joshthinks resources for readers who want to go deeper
- Sources
How Cold War priorities translated into financial change
Security logic drove every major financial innovation of the postwar era. Here is how each channel worked:
- Institution-building. The 1944 Bretton Woods agreement created near-fixed exchange rates anchored to a dollar convertible into gold, then spawned the IMF and World Bank to manage payments imbalances and fund reconstruction. The Marshall Plan channeled a substantial amount into Western Europe, building dollar-denominated investment networks that locked allies into U.S. financial circuits. GATT progressively dismantled tariffs, expanding markets for private capital.
- Fiscal normalization. Maintaining hundreds of overseas bases and a nuclear deterrent required continuous spending. Historians argue that Cold War defense commitments normalized deficit spending and legitimized creative budget accounting, making large peacetime military budgets compatible with Keynesian growth narratives.
- Monetary and market engineering. The Exchange Stabilization Fund gave the Treasury a discretionary tool to intervene in currency markets without congressional approval. Federal Reserve swap lines provided emergency dollar liquidity to allied central banks. IMF credits backstopped balance-of-payments crises before they became political crises.
- Economic statecraft. Sanctions, aid conditionality, and covert influence redirected trade flows, created captive markets, and punished adversaries without firing a shot.
- Market-level transformation. Soviet fears of U.S. asset seizure pushed dollar deposits offshore into European banks, accidentally seeding the Eurodollar market — an unregulated dollar liquidity pool that eventually dwarfed domestic U.S. banking.
How Bretton Woods, the IMF, the World Bank, the Marshall Plan, and GATT structured international finance
The postwar institutional architecture was not accidental. It was designed to serve both economic reconstruction and U.S. strategic objectives, as scholarly syntheses of the period make clear.
| Year | Event | Financial role |
|---|---|---|
| 1944 | Bretton Woods Conference | Established near-fixed exchange rates; dollar convertible to gold; created IMF and World Bank mandates |
| — | IMF and World Bank operational | IMF provided short-term balance-of-payments credit; World Bank funded long-term reconstruction lending |
| — | GATT signed | Reduced tariffs progressively, expanding trade volumes and dollar-denominated commerce |
| — | Marshall Plan begins | U.S. aid rebuilt Western European industry, deepened dollar dependency, and contained Soviet influence |
The Harvard DASH analysis of Bretton Woods documents how the agreement set the early postwar monetary rules: near-fixed exchange rates, gold convertibility for monetary authorities, and IMF/World Bank functions for postwar adjustment credit. Political scientist John Ruggie called this arrangement “embedded liberalism” — markets were open, but states retained enough policy space to manage domestic stability. That balance was itself a Cold War bargain: capitalism had to look better than the alternative.
The Soviet Union’s relationship to these institutions was more complicated than the bipolar narrative suggests. Cambridge Core research shows the USSR engaged with the liberal world order rather than existing in total autarky, which meant global institutions exerted real pressure on Soviet economic choices.
How Cold War strategy changed U.S. and global fiscal and monetary practice
Cold War commitments normalized deficit finance and produced new monetary backstops that would have been unthinkable in the prewar era.
- Deficit normalization. Permanent military readiness required spending that could not be turned off between crises. Policymakers used creative accounting — treating stockpiles as capital assets, for instance — to preserve fiscal space for continuous defense outlays, reshaping U.S. fiscal practice in ways that outlasted the Cold War itself.
- The Nixon shock (1971). By the late 1960s, Vietnam War spending and balance-of-payments deficits had drained U.S. gold reserves. On August 15, 1971, President Nixon suspended dollar-gold convertibility, ending the Bretton Woods fixed-rate system. By 1973, major currencies were floating freely. The immediate cause was fiscal: the U.S. could not sustain both guns and the gold window.
- Exchange Stabilization Fund. Created in 1934 but heavily used during the Cold War, the ESF gave the Treasury Secretary authority to intervene in currency and gold markets without congressional appropriation — a discretionary tool suited to fast-moving geopolitical crises.
- Federal Reserve swap lines. The Fed extended reciprocal currency arrangements to allied central banks from the early 1960s onward, providing emergency dollar liquidity when balance-of-payments pressures threatened allied stability.
- IMF Special Drawing Rights (SDRs). Created in 1969 to supplement gold and dollar reserves, SDRs gave the IMF a synthetic reserve asset that could be allocated to members facing liquidity shortfalls — a direct response to the dollar shortage that Cold War spending had created.
The scale of offshore dollar dependency became visible in 2008, when the Fed improvised swap lines approaching several hundred billion dollars in emergency lending to stabilize offshore dollar markets that had frozen — a direct descendant of the Eurodollar system seeded by Cold War geopolitics.
That figure, documented in Eurodollar market analysis, shows how far the Cold War’s monetary improvisation had traveled by the twenty-first century.
How aid, sanctions, and covert influence reshaped trade and markets
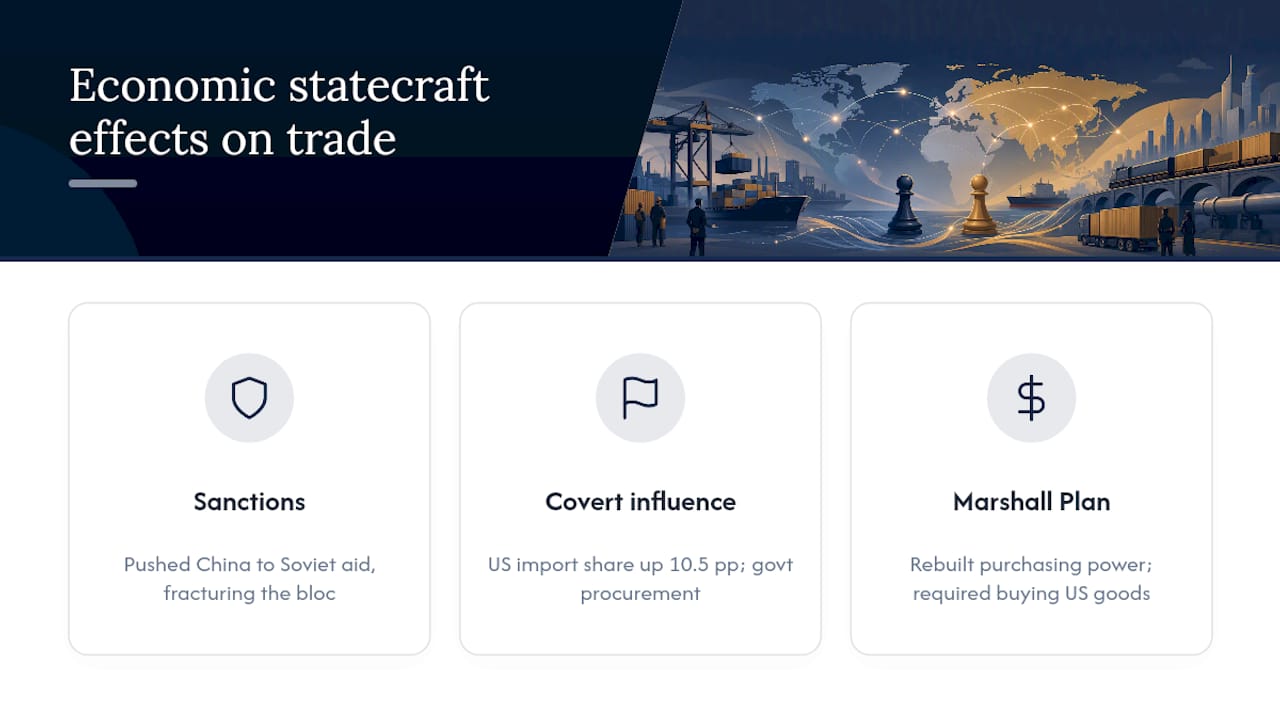
Economic statecraft — the use of financial tools for political ends — was not a Cold War invention, but the period industrialized it. The Stanford University Press study of economic sanctions argues that while sanctions rarely achieved their immediate political aims, they produced significant long-term structural effects. The clearest example: U.S. and allied sanctions on China in the 1950s pushed Beijing to demand Soviet aid and technology, straining Sino-Soviet relations in ways that eventually fractured the communist bloc.
The covert dimension had measurable trade consequences. An NBER working paper using declassified CIA intervention records finds that U.S. covert interventions were followed by a statistically significant increase in the share of imports purchased from the U.S. — roughly 10.5 percentage points in the authors’ sample. The effect was concentrated where government purchases were large, consistent with trade diversion rather than genuine trade creation.
Pro Tip: When reading empirical studies on CIA interventions and trade, distinguish between government procurement (which can be directed by a new regime) and private-sector trade flows. The NBER finding reflects the former more than the latter — a meaningful caveat for anyone using these numbers to argue about market efficiency.
The Marshall Plan followed the same logic. Reconstruction aid rebuilt European purchasing power, but it also required recipients to buy American goods, deepening dollar dependency and expanding U.S. export markets simultaneously. Aid was never purely humanitarian; it was American geopolitics expressed in dollars.
How banking, capital mobility, and offshore dollar markets developed through the Cold War
The Eurodollar market is the Cold War’s most consequential and least-discussed financial legacy. Soviet banks, fearing the U.S. would freeze their dollar deposits after Korea, moved those deposits to European banks outside U.S. jurisdiction. Regulatory arbitrage did the rest: European banks could pay higher interest on dollar deposits than U.S. banks could under Regulation Q, so the pool grew rapidly through the 1960s and 1970s.
The downstream effects were profound:
- Expanded capital mobility. Eurodollar lending bypassed national capital controls, accelerating the financialization of the global economy and reducing governments’ ability to manage domestic credit conditions.
- Petrodollar recycling. After OPEC’s 1973 oil embargo and the 1979 price shock, oil revenues denominated in dollars flooded into Western banks, which recycled them as loans to developing countries and communist regimes — creating the sovereign debt vulnerabilities that exploded in the 1980s.
- Synchronized crises. The 1979–82 Volcker shock — the Fed’s aggressive rate hikes to break inflation — raised LIBOR sharply, making floating-rate Eurodollar loans ruinously expensive. Anthony Pennings’ analysis shows how the USSR, which had borrowed heavily in Eurodollar markets, found those same markets strangling its external finances by the mid-1980s.
- 2008 swap-line improvisation. When Eurodollar funding froze in 2008, the Fed had no formal framework for the scale of intervention required. The swap lines it extended were ad hoc, built on Cold War precedents but operating at a magnitude those precedents never anticipated.
Poland’s 1981 debt crisis previewed the pattern. Research on sovereign debt and Cold War crisis shows how growing international borrowing and subsequent default limited Eastern Bloc policy options and accelerated domestic political instability — debt markets doing what armies could not.
Key Cold War finance turning points from 1944 to 1991
| Year | Event | Financial consequence |
|---|---|---|
| 1944 | Bretton Woods Conference | Dollar-gold standard established; IMF and World Bank created |
| — | IMF and World Bank operational | International payments system formalized; adjustment credit available |
| — | Marshall Plan begins | Dollar networks embedded in Western Europe; U.S. export markets expanded |
| 1969 | SDRs created | Synthetic IMF reserve asset supplements gold and dollar reserves |
| 1971 | Nixon shock | Dollar-gold convertibility suspended; Bretton Woods fixed rates collapse |
| 1973 | Major currencies float | Exchange-rate risk becomes a permanent feature of global finance |
| 1973–1973 | OPEC oil shocks | Petrodollar recycling accelerates; inflation and balance-of-payments crises spread |
| 1979–82 | Volcker shock | Fed raises rates aggressively; floating-rate sovereign debt becomes unsustainable |
| 1980s | Developing-world debt crises | IMF conditionality expands; Western banks gain leverage over sovereign borrowers |
| — | Cold War ends | Eastern Bloc creditworthiness collapses; dollar-based order faces no systemic rival |
Why Cold War financial legacies still matter today
The Cold War’s financial architecture did not retire in 1991. It evolved into the operating system of the present global economy.
- Dollar dominance. The Bretton Woods system established the dollar as the world’s reserve currency. Even after Nixon ended gold convertibility, dollar dominance persisted because oil was priced in dollars (the petrodollar arrangement), trade invoicing followed dollar norms, and no rival had the depth of U.S. Treasury markets.
- Sanctions as a primary tool. The sanctions toolkit refined against the Soviet bloc — OFAC designations, export controls, financial exclusion — is now deployed against Iran, Russia, and others. The architecture is Cold War infrastructure repurposed.
- Fed swap lines as a permanent backstop. What began as a Cold War liquidity tool for allies is now a standing feature of the global financial system, extended to major central banks and activated in every major crisis since 2008.
- SDRs and IMF conditionality. Special Drawing Rights remain the IMF’s reserve asset. IMF lending programs still carry the conditionality logic developed during Cold War-era stabilization packages.
- Sovereign debt vulnerability. Countries that borrowed heavily in dollar-denominated markets during the Cold War era still carry that currency risk. Rising U.S. interest rates transmit directly to their debt-service costs — a Cold War-era mechanism still running.
For individual readers, these legacies show up in pension fund exposure to dollar-denominated assets, inflation driven partly by petrodollar dynamics, and the currency risk embedded in any internationally diversified portfolio.
A perspective on political economy and practical finance
Most financial commentary treats institutions like the IMF or the dollar’s reserve status as natural features of the economic landscape. They are not. They are political settlements, built under specific pressures, that could be rebuilt differently under different pressures. The Cold War makes that visible in a way that peacetime economics tends to obscure.
What strikes me most about this history is how often financial innovation was improvised under duress. The Eurodollar market was not designed; it emerged from Soviet fear and regulatory arbitrage. Fed swap lines were not planned; they were invented when the alternative was allied financial collapse. The lesson for anyone tracking today’s financial system is that the next structural shift will probably look the same: a geopolitical shock forcing an improvised response that then becomes permanent infrastructure.
Joshthinks resources for readers who want to go deeper
If this history of Cold War finance has you asking how these structures actually function today, Joshthinks has the resources to take you further.

Start with the Bretton Woods deep dive — it unpacks the 1944 agreement in full, including the political negotiations that shaped the dollar’s reserve role. Then watch When Volcker Broke the Market, which connects the 1979–82 rate shock directly to today’s interest-rate environment. For readers who want to understand how these historical forces translate into market instruments, the Finance & Markets section covers futures, monetary policy, and financial history in the same evidence-grounded style. These are Joshthinks’ own materials, produced to give you the political-economy context that most finance sites skip.
Sources
- Economic Cold War | Stanford University Press
- Banking on the Cold War | Boston Review
- Harvard DASH — excerpt on Bretton Woods and postwar monetary cooperation
- NBER working paper on CIA interventions and trade
- Sagix
- The Hangman’s Rope: How the USSR Created the Eurodollar Market that Later Strangled It — Anthony J. Pennings
- Scholarly article on postwar economic policy and Bretton Woods (DOI)
- Capitalism’s fellow traveler: the Soviet Union, Bretton Woods, and the Cold War — Cambridge Core


