

What Are Financial Futures? A 2026 Investor’s Guide
Financial futures are standardized, exchange-traded contracts that obligate two parties to buy or sell a financial instrument at a set price on a specific future date. These contracts cover intangible assets like stock indices, interest rates, and currencies, and they settle almost exclusively in cash. CME Group, the world’s largest futures exchange, lists hundreds of these contracts. Whether you want to hedge a portfolio or speculate on rate movements, understanding financial futures is the starting point for every serious trader.
What are financial futures and why do they matter?
Financial futures are legally binding agreements traded on regulated exchanges, not between private parties. That distinction matters enormously. Financial futures were introduced in 1972 with currency contracts designed to hedge exchange rate risk after the Bretton Woods monetary system collapsed. That origin story reveals their core purpose: transferring financial risk from those who cannot afford it to those willing to take it on.
The financial futures meaning is straightforward in structure but powerful in application. A buyer agrees to receive a financial instrument at a fixed price. A seller agrees to deliver it. At expiration, the contract settles in cash based on the difference between the agreed price and the market price. No stock certificates change hands. No currency physically moves. Only the net profit or loss transfers.
Common examples include S&P 500 index futures, Eurodollar futures, Treasury bond futures, and currency futures. These products give investors exposure to entire markets, interest rate curves, or foreign exchange rates through a single contract. That breadth of access, combined with leverage, is why institutions and individual traders alike use them every day.
How do financial futures contracts work?
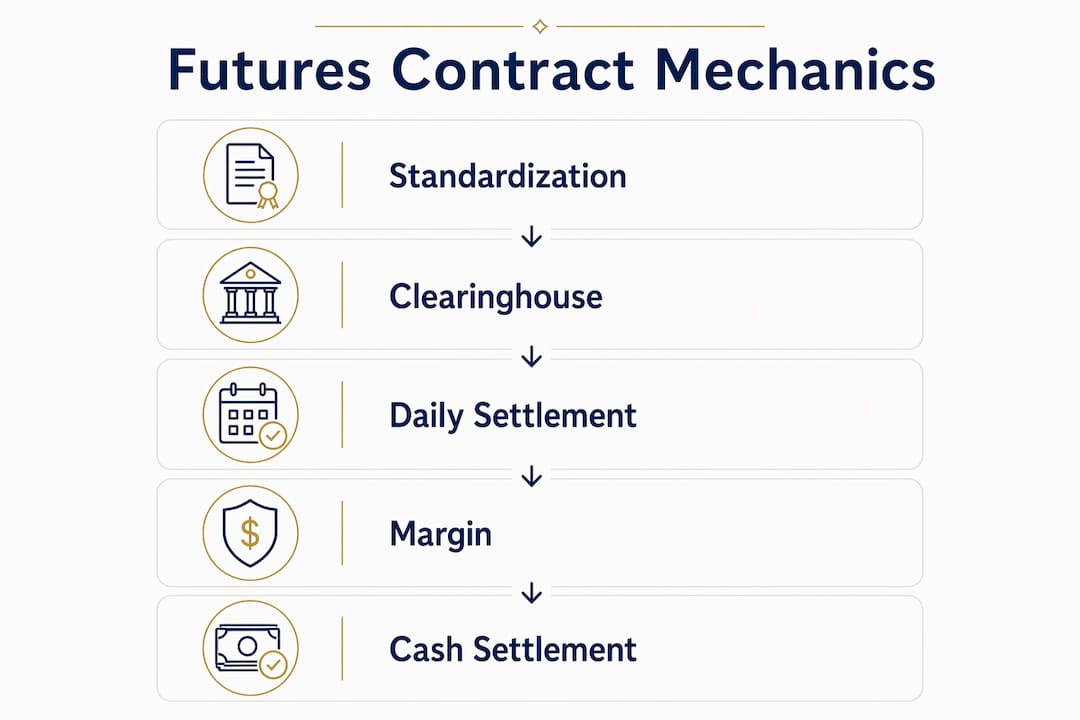
The mechanics of a futures contract rest on three pillars: standardization, a clearinghouse, and daily settlement. Each one solves a problem that private contracts cannot.
Standardization means every E-mini S&P 500 contract has identical terms. The contract size, tick value, expiration date, and settlement method are fixed by the exchange. That uniformity creates deep liquidity because every buyer and seller is trading the exact same instrument.
The clearinghouse eliminates counterparty credit risk by standing between every buyer and seller. When you buy a futures contract on CME Group, your counterparty is technically the clearinghouse, not another trader. This is the cornerstone of futures market stability and the main reason futures are trusted by pension funds, banks, and retail traders alike.
Daily mark-to-market settlement is the third pillar. At the end of each trading day, gains and losses are calculated and credited or debited to your account in cash. This process prevents losses from accumulating unnoticed over weeks. It also means your account balance reflects your real position every single morning.
Cash settlement means no physical asset delivery occurs at expiration. The contract simply closes at the final settlement price, and the net difference moves between accounts. This is why financial futures are accessible to traders who have no interest in owning Treasury bonds or foreign currency.
Pro Tip: Treat margin in futures as a performance bond, not a down payment. You are not buying the underlying asset. You are posting collateral to guarantee your daily obligations.
One important concept for beginners is the difference between futures and forwards. Forwards are private, customized contracts between two parties with no clearinghouse and no daily settlement. Futures are public, standardized, and exchange-cleared. Forwards carry counterparty risk. Futures do not. That difference explains why large institutions prefer futures to isolate and transfer financial risks with liquidity and transparency that private forwards cannot match.
What types of financial futures exist?
Financial futures fall into three major categories: equity index futures, interest rate futures, and currency futures. Each category serves a distinct purpose and attracts different types of traders.
| Category | Example Contract | Primary Use |
|---|---|---|
| Equity Index | E-mini S&P 500 (ES), Micro E-mini (MES) | Broad market exposure, portfolio hedging |
| Interest Rate | Eurodollar, Treasury Bond (ZB) | Rate risk management, yield curve trading |
| Currency | Euro FX, Japanese Yen futures | Foreign exchange hedging, FX speculation |
Common financial futures like the E-mini S&P 500 represent $50 times the index value, making one contract worth roughly $275,000 at current levels. That size puts it out of reach for many retail traders. Micro E-mini contracts, introduced by CME Group, solve that problem by offering one-tenth the size. The Micro E-mini S&P 500 (MES) requires far less capital and is now the entry point most beginners use.
Interest rate futures like Eurodollar contracts and Treasury bond futures let traders express views on Federal Reserve policy or the shape of the yield curve. Currency futures on the Chicago Mercantile Exchange cover the euro, Japanese yen, British pound, and more. Each contract has standardized specifications including tick size, trading hours, and expiration cycles.
Key contract specifications you need to know before trading:
- Contract size: The notional value one contract controls
- Tick size: The minimum price movement and its dollar value
- Expiration cycle: Quarterly (March, June, September, December) for most index futures
- Trading hours: Most financial futures trade nearly 24 hours on electronic platforms like CME Globex
How does margin and leverage work in futures trading?
Margin in futures trading is a performance bond, not a loan. You deposit a fraction of the contract’s total value to open and hold a position. Futures margin requires only 3–12% of the contract’s notional value. That ratio creates significant leverage.
Here is what leverage means in practice:
- You control a large position with a small deposit. A $275,000 E-mini S&P 500 contract might require $15,000 in initial margin. A 1% move in the index produces a $2,750 gain or loss on your $15,000 deposit. That is an 18% swing on your capital.
- Gains and losses are amplified equally. Leverage does not favor the direction you choose. A wrong-way move of 2% wipes out more than a third of your margin deposit.
- Daily mark-to-market means losses hit immediately. Unlike stocks where a paper loss sits unrealized, futures losses are debited from your account each evening. If your balance falls below the maintenance margin level, you receive a margin call and must deposit more funds or close the position.
- Liquidation risk is real. If you cannot meet a margin call, the broker closes your position at the market price, locking in the loss.
Professional traders maintain liquidity 2 to 5 times the exchange-required margin. That buffer absorbs daily volatility without triggering a forced liquidation. Retail traders who fund accounts to the bare minimum are one bad session away from losing their entire position.
Pro Tip: Never trade futures with only the minimum margin in your account. Fund at least twice the initial margin requirement to give your position room to breathe through normal daily price swings.
Leverage in futures also has a tax advantage in the United States. Many financial futures qualify as Section 1256 contracts, taxed under the 60/40 rule. Sixty percent of gains are treated as long-term capital gains and forty percent as short-term, regardless of how long you held the position. For active traders, that blended rate is often lower than paying short-term rates on every trade. You can explore how leverage amplifies both gains and risks in more depth before committing real capital.
What are the practical uses of financial futures in investing?
Financial futures serve two main groups: hedgers who offset existing portfolio risks and speculators who seek profits from price movements. Knowing which group you belong to changes every decision you make.
Hedgers use futures to lock in prices and reduce uncertainty. A portfolio manager holding $10 million in S&P 500 stocks can sell E-mini futures to offset downside risk without selling the actual stocks. This approach avoids triggering capital gains taxes while still protecting against a market decline. Corporations use currency futures to lock in exchange rates for future international transactions.
Speculators take the other side of those hedges. They have no underlying exposure to protect. They simply form a view on where prices are heading and use leverage to profit from that view. A speculator who believes the Federal Reserve will raise rates might short Treasury bond futures. If rates rise and bond prices fall, the short position profits.
Portfolio managers use futures for quick market exposure. Buying E-mini S&P 500 futures is faster and cheaper than buying 500 individual stocks. Futures also allow managers to go short, something difficult to do efficiently with a stock portfolio.
Over 99% of financial futures positions are closed by offsetting trades before expiration. Physical delivery almost never happens. Traders simply buy back a short or sell a long before the contract expires. This behavior reflects the reality that most participants want price exposure, not the underlying asset.
One cost that beginners overlook is the roll cost and cost of carry. When you hold a futures position across an expiration date, you must close the expiring contract and open the next one. The price difference between those two contracts, the roll cost, can silently erode profits over time. Interest rates and dividends embedded in the futures price also affect your returns. These costs are small per trade but compound significantly for long-term strategies.
Common pitfalls for new futures traders:
- Underestimating how fast leverage amplifies losses
- Ignoring roll costs on positions held across contract expirations
- Treating minimum margin as sufficient account funding
- Confusing futures with options, which carry different rights and obligations
Key takeaways
Financial futures are standardized, exchange-traded contracts that use leverage, clearinghouse protection, and daily cash settlement to give investors precise control over financial risk.
| Point | Details |
|---|---|
| Core definition | Financial futures obligate parties to buy or sell a financial instrument at a set price and date. |
| Clearinghouse protection | The clearinghouse eliminates counterparty risk, making futures safer than private forward contracts. |
| Margin and leverage | Futures require only 3–12% of notional value as margin, amplifying both gains and losses significantly. |
| Cash settlement | Over 99% of contracts close before expiration; no physical asset delivery occurs in financial futures. |
| Two user types | Hedgers reduce existing risk; speculators seek profit from price movement using leverage. |
Why most beginners get futures backwards
Most new traders approach financial futures the wrong way. They focus on the profit potential first and learn the mechanics second. That order gets people hurt.
The single most important thing I have learned from studying futures markets is this: the margin system is not a gift. It is a daily obligation. Every morning your account is marked to market. Every morning you either have enough capital to stay in the trade or you do not. There is no grace period, no averaging down without consequence, and no waiting for the market to come back to you if your margin runs dry.
The second thing most beginners miss is contract specifications. The E-mini S&P 500 and the Micro E-mini S&P 500 look similar on a chart. But one contract controls ten times the dollar value of the other. Trading the wrong contract size is not a minor error. It is the difference between a manageable loss and a blown account.
I also think the tax treatment of Section 1256 contracts is one of the most underappreciated advantages in retail trading. The 60/40 rule means active futures traders often pay a lower blended tax rate than stock traders who hold positions for less than a year. Most people never factor that into their return calculations.
My honest recommendation: read the contract specifications before you look at a chart. Understand what one tick is worth in dollars. Know your margin requirement and then double it before you fund the account. The traders who survive long enough to get good at this are the ones who respected the mechanics first.
— Josh
Start trading smarter with Joshthinks
If this article gave you a clearer picture of how financial futures work, the next step is putting that knowledge into practice with real contract examples.

Joshthinks has a practical, beginner-focused guide built specifically for traders stepping into futures for the first time. The MES futures trading guide walks through the Micro E-mini S&P 500 contract in detail, covering entry strategies, margin management, and the mistakes most new traders make in their first month. For broader market context and ongoing education, the finance and markets hub covers everything from interest rate dynamics to portfolio strategy. These resources are built for people who want to understand what they are trading before they risk real money.
FAQ
What is a futures contract in simple terms?
A futures contract is a legally binding agreement to buy or sell a financial instrument at a fixed price on a specific future date. Most financial futures settle in cash, meaning no physical asset changes hands.
How are financial futures different from options?
Futures obligate both parties to complete the transaction at expiration. Options give the buyer the right but not the obligation to buy or sell. That difference makes futures riskier for buyers who do not close their positions before expiration.
What is the minimum capital needed to trade financial futures?
Margin requirements vary by contract and broker, but futures margin typically represents 3–12% of the notional contract value. Experienced traders recommend holding at least twice the minimum margin to avoid forced liquidation from daily price swings.
Do financial futures involve physical delivery?
Rarely. Over 99% of futures positions are closed before expiration through offsetting trades. Financial futures tied to stock indices and interest rates are cash-settled by design.
Are financial futures taxed differently than stocks?
Yes. In the United States, most financial futures qualify as Section 1256 contracts. Gains and losses are taxed under the 60/40 rule, with 60% treated as long-term and 40% as short-term capital gains, regardless of how long the position was held.


