

U.S. Trustees: Map Federal Trust Rules to Trust Fund Accounting
Trust fund accounting is the trustee’s formal record of every deposit, disbursement, income item, and expense flowing through a trust, sorted by whether it belongs to principal or income. A trustee, or sometimes a CPA working on the trustee’s behalf, prepares it on a schedule set by the trust instrument, state law, or a beneficiary’s formal request. The goal is simple: give beneficiaries and courts a transparent, auditable trail showing exactly where the money went and why.
TL;DR:
- Trust fund accounting must clearly differentiate between receipts, disbursements, income, and principal, with accurate tagging for each transaction.
- Monthly reconciliation of transactions against source documents like bank statements and invoices is essential for audit readiness.
- Trust reports should include detailed schedules and supporting documents, with key data such as dates, amounts, beneficiaries, and purposes.
- Federal trust funds follow strict standards using USSGL conventions, and private trusts should adopt similar disciplined recordkeeping practices.
- Regular internal reviews and maintaining comprehensive documentation can prevent red flags during audits and reduce liability for trustees.
Table of Contents
- What Trust Fund Accounting Actually Covers
- Building a Recordkeeping System That Survives Scrutiny
- The Federal Standards Behind Trust Fund Accounting
- How to Prepare a Trust Accounting Step by Step
- What Belongs in a Trust Accounting Report
- Reconciliation, Audit Readiness, and Warning Signs
- Trustee Liability and Responding to Beneficiary Requests
- JoshThinks’ Practical Checklist for Real-World Trustees
- Tracking and Valuing Trust Investments
- Tax Considerations for Trust Income and Distributions
- Internal and External Audits for Trust Accounts
- How Accounting Differs by Trust Type
- Where to Find Official Guidance
- What Most Guides Get Wrong About Trust Accounting
- Sources
What Trust Fund Accounting Actually Covers
Every trust accounting revolves around a small set of terms that sound simple but trip up first-time trustees constantly. Receipts are money coming in: dividends, rental income, interest, or a lump-sum contribution from the grantor. Disbursements are money going out: trustee fees, beneficiary distributions, tax payments, property maintenance. Income typically means what the trust’s assets generate (interest, dividends, rent), while principal is the underlying corpus itself, like the original stock portfolio or real estate. Getting that distinction wrong is the single most common error in trust fund reporting, because many trusts direct income to one beneficiary and principal to another entirely.
A complete accounting usually includes several standard schedules:
- A trial balance showing every account’s ending balance before the report is finalized
- A receipts and disbursements schedule, itemized by date and category
- A statement of changes in principal and income, showing the beginning balance, activity, and ending balance separately
- Beneficiary ledgers, tracking exactly what each named beneficiary received or is owed
Account types matter too. A trust typically runs through a dedicated checking account, one or more investment accounts, and occasionally a separate account for real property expenses. Law firms handling client funds use a different structure entirely, called an IOLTA (Interest on Lawyers’ Trust Accounts), which the American Bar Association governs through model rules that individual state bars adopt with their own variations.
Building a Recordkeeping System That Survives Scrutiny
A trust accounting is only as strong as the paper trail behind it. Courts, auditors, and skeptical beneficiaries do not accept a spreadsheet with numbers typed in from memory. They want source documents: bank statements, deposit slips, canceled checks, invoices, and receipts for every material transaction.
Set up your ledger structure before money starts moving, not after. That means:
- Create a master ledger for the trust as a whole, then beneficiary subledgers if there are multiple beneficiaries with different interests in income versus principal.
- Tag every transaction with its purpose (distribution, fee, tax payment, investment purchase) and the beneficiary it affects, if any.
- Reconcile monthly against bank and brokerage statements rather than waiting for year-end, which is where small errors compound into large ones.
- Retain records for at least seven years, longer if the trust document, state law, or an ongoing dispute requires it.
- Document who performed each reconciliation and when, since auditors specifically look for evidence that someone independent checked the numbers.
Pro Tip: Build a one-page reconciliation log that lives outside the accounting software: date, who reconciled, what didn’t match, and how it got resolved. When a beneficiary’s attorney asks for proof of process eighteen months later, that log is worth more than the ledger itself.
The trustees for the Social Security Administration’s OASI Trust Fund follow this same discipline at a massive scale. Their reserves totaled $2,538.3 billion at the end of 2024, and every dollar of that balance traces back to a reconciled, documented transaction. The scale differs from a family trust by orders of magnitude, but the underlying discipline, reconcile, document, retain, is identical.
The Federal Standards Behind Trust Fund Accounting
Federal trust funds do not operate on ad hoc rules. They follow a layered framework built by three bodies: the Federal Accounting Standards Advisory Board (FASAB), which sets the accounting standards federal entities must apply; the U.S. Department of the Treasury, through its Bureau of the Fiscal Service, which issues operational guidance and runs the monthly reporting cycle; and the Office of Management and Budget (OMB), which oversees budget execution.
Together, Treasury, OMB, and FASAB require federal trust funds to track income and disbursements using U.S. Standard General Ledger (USSGL) conventions, and funds are authorized only for the specific purposes their enabling legislation names. This matters for private trustees too, because it is the closest thing the country has to a national template for what disciplined trust reporting looks like.
A few specifics worth knowing:
- USSGL guidance shows that trust funds record incoming money as appropriated trust receipts under account code 4114, and use specialized transfer accounts (5750, 5755, 5760, 5765) instead of the standard appropriation accounts other federal agencies use.
- The Fiscal Service’s Funds Management program publishes monthly trial balances and balance sheets for Treasury-managed trust funds, giving a real-world model of report formatting.
- For law firms and other client-fund fiduciaries, ABA model rules and each state’s own IOLTA rules govern client trust accounts, and those rules vary meaningfully by state, so check your local bar’s requirements directly rather than assuming a national standard applies uniformly.
How to Prepare a Trust Accounting Step by Step
Most trustees freeze the first time they are asked to “provide an accounting.” The process is mechanical once you break it down.
Step 1: Confirm authority and frequency. Read the trust instrument first. It usually specifies how often an accounting is due (annually is common) and to whom it must go. If the document is silent, state law fills the gap, and many states require accounting at least annually or upon a beneficiary’s written request.
Step 2: Gather source documents and set up ledgers. Pull twelve months of bank and brokerage statements, every invoice paid, every deposit received. Open (or confirm) your ledger structure before entering a single transaction.
Step 3: Post transactions with tags. Every entry gets a beneficiary tag (if applicable) and a principal-or-income classification. This is the step people rush, and it’s the one that causes disputes later.
Step 4: Reconcile everything. Match every ledger entry to a bank or brokerage statement line. Investment accounts need special attention here, since accrued interest and amortized premiums do not always show up as a clean cash movement.
Step 5: Build the report. Show opening balances, total receipts, total disbursements, allocations between principal and income, and ending balances. Attach supporting schedules for anything material, an itemized list of distributions, a fee schedule, an investment summary.
Step 6: Get an independent review where the stakes justify it. A CPA or trust attorney reviewing the accounting before it goes to beneficiaries catches errors early and adds a layer of credibility that self-prepared reports lack.
Pro Tip: If a trust holds anything beyond a simple bank account, maintain a book ledger and a cash ledger side by side. Reconcile interest accruals and investment amortization every month. Federal trust fund reporting for Social Security follows exactly this logic, tracking income against cost separately in its statement of operations rather than lumping everything into one number.
What Belongs in a Trust Accounting Report
A usable accounting report does not need to be elaborate, but it does need consistent fields across every line item:
- Date of the transaction
- Transaction type (distribution, receipt, fee, tax payment, investment purchase or sale)
- Payee or source of the money
- Amount
- Allocation to principal or income
- Beneficiary affected, if the transaction is beneficiary-specific
- Memo explaining the purpose, especially for anything unusual
- Supporting document reference, a file name or invoice number tying the entry back to proof
Summaries should roll up into a few supporting schedules: an investment activity summary, a fee schedule showing what the trustee charged and why, and a beneficiary distribution schedule. Most trustees now keep these as a combination of spreadsheet ledgers and a folder of scanned PDFs, bank statements, invoices, an index mapping each memo line to its supporting file. It doesn’t need to be fancy. It needs to be traceable.
Reconciliation, Audit Readiness, and Warning Signs
Reconcile monthly if the trust has any investment activity; quarterly is the bare minimum for a simple cash-only trust. When numbers don’t match, stop and find the discrepancy before moving forward, don’t just plug the difference and hope it washes out later.
An auditor reviewing a trust accounting typically checks:
- Supporting documentation for every material disbursement
- Evidence that each distribution was authorized under the trust instrument
- Meeting minutes or written trustee decisions for discretionary distributions
- Fee schedules and whether charged fees match what was disclosed
Auditors specifically look for documented authority behind each disbursement, proof the trust instrument actually permits that purpose and that beneficiary. A handful of red flags trigger closer scrutiny almost every time: commingled funds, journal entries with no clear explanation, reports filed months late, or missing source documents for large transactions.
Pro Tip: Documenting who reconciled an account and when, along with any corrective action taken, eliminates most audit red flags before an auditor even asks the question.
Trustee Liability and Responding to Beneficiary Requests
Trustees owe beneficiaries a fiduciary duty that leaves little room for sloppiness. Keep trust assets completely separate from personal or business funds, since commingling is one of the fastest paths to a breach-of-duty claim. Disclose fees plainly and explain the reasoning behind any discretionary allocation decision.
- If a trustee refuses or fails to provide an accounting, beneficiaries can formally demand one in writing, then petition a court to compel it if the trustee still refuses.
- Courts can remove a trustee, impose personal liability, or order restitution in serious cases.
- Engage a CPA or trust attorney the moment a dispute surfaces, and document every remediation step taken in response.
JoshThinks’ Practical Checklist for Real-World Trustees
Trust fund accounting rewards consistency over complexity. Report on a fixed cadence, even if the instrument only requires annual reporting, quarterly check-ins catch problems early. Add narrative footnotes to anything unusual, a one-time legal settlement, an odd fee, a discretionary distribution. Set a personal threshold, once a trust holds real estate or a mixed investment portfolio, bring in a CPA. Combine that with the budgeting discipline outlined in our faith-based planning guide, and most trustees can run a defensible accounting without outside help most months of the year.
Tracking and Valuing Trust Investments
Investment-holding trusts need two ledgers running in parallel: a cash ledger tracking actual money movement, and a book ledger tracking accruals, amortization of bond premiums or discounts, and unrealized gains. Skip the book ledger and you’ll eventually face a large, unexplained adjustment at year-end that looks like an error even when it isn’t.
Valuation typically happens at fair market value on the accounting date, using brokerage statements as the primary source for publicly traded securities. Illiquid assets, closely held business interests, real estate, private equity stakes, need periodic professional appraisals, since a trustee guessing at value opens the door to a beneficiary dispute over undervaluation or overvaluation.
Reconcile interest accruals and any amortization monthly rather than letting it pile up. This practice mirrors how federal trust funds treat their holdings: the Social Security trust funds do not hold cash sitting idle. Instead, surplus receipts convert into special-issue Treasury securities, an accounting mechanism, not a literal vault of money. Private trusts don’t use special-issue securities, but the underlying principle carries over: the trustee’s job is to track what an asset is actually worth right now, not what it cost when the trust acquired it, and to document that valuation method consistently from one report to the next.
Tax Considerations for Trust Income and Distributions
Trusts face a tax structure that differs meaningfully from individual returns. A trust generally gets a deduction for income it distributes to beneficiaries, who then report that income on their own returns, this is the core mechanic behind Schedule K-1 reporting. Income the trust retains instead of distributing gets taxed at the trust level, and trust tax brackets compress much faster than individual brackets, meaning even modest retained income can land in a high marginal rate.
The principal-versus-income split done throughout the year isn’t just a bookkeeping exercise, it directly determines what gets reported as taxable distributable net income (DNI) versus what passes through as a tax-free return of principal. Get that allocation wrong during the year and the tax return built on top of it will be wrong too.
Grantor trusts, irrevocable trusts, and charitable trusts each carry distinct tax treatment, and a trustee moving from managing a revocable living trust to an irrevocable one after the grantor’s death needs to recognize that the tax rules shift substantially at that transition point. This is one area where a CPA experienced in fiduciary tax returns earns their fee many times over, filing errors here compound annually.
Internal and External Audits for Trust Accounts
Internal audits, meaning the trustee’s own periodic self-review, catch the majority of errors before they ever reach a beneficiary or a court. That means the monthly reconciliation habit described earlier, checked against a simple internal checklist: does every disbursement have a supporting document, does every discretionary distribution have documented reasoning, do the ledgers tie to the bank statements.
External audits come into play when a beneficiary formally disputes an accounting, when a court orders one as part of litigation, or when the trust is large enough that an independent CPA review is standard practice regardless of disputes. An external auditor works through the same checklist an internal review does, but with no incentive to give the trustee the benefit of the doubt on an ambiguous entry.
Compliance checks for federal trust funds work on a similar internal/external split, agencies produce monthly internal reports through the Fiscal Service’s Funds Management program, while outside reviews and the annual SSA Trustees Report serve as the external-facing compliance layer for Social Security’s trust funds specifically. Private trustees can borrow that structure directly: frequent internal reconciliation, paired with a periodic outside check when the trust’s size or complexity justifies the cost.
How Accounting Differs by Trust Type
A revocable living trust, while the grantor is alive, usually requires the lightest accounting burden, since the grantor can typically access records directly and often serves as trustee. Once the grantor dies and the trust becomes irrevocable, accounting obligations tighten considerably. Successor trustees now answer to beneficiaries who have real, enforceable rights to see the numbers.
Irrevocable trusts built for asset protection or estate tax planning demand the strictest discipline, because beneficiaries have no ability to unwind the trust if they’re unhappy, formal accounting is often their only real window into how the trust is managed. These trusts also see the most disputes, so airtight documentation matters more here than anywhere else in private trust practice.
Charitable trusts add a layer most private trusts never encounter: state attorney general oversight, since charitable assets are considered to serve a public purpose rather than a private beneficiary’s interest. Charitable remainder trusts and charitable lead trusts also carry specific IRS reporting requirements (Form 5227, for instance) on top of standard trust accounting, and missing those filings creates problems independent of whether the underlying accounting itself was accurate.
Where to Find Official Guidance
For federal trust funds, start with the Bureau of the Fiscal Service’s federal trust fund guidance and the annual SSA Trustees Report for real reporting examples. For private trust and client-fund accounting, the ABA’s model rules on trust account records and your state bar’s IOLTA program are the authoritative starting points.
What Most Guides Get Wrong About Trust Accounting
Most advice on this topic treats trust fund accounting as a compliance chore, something to survive rather than something to use. That framing misses the point. The trustees behind Social Security’s trust funds don’t publish detailed statements of operations because the law forces them to in some narrow technical sense, they do it because a decrease in reserves of $103.2 billion in 2024 need a paper trail that survives public scrutiny for decades.
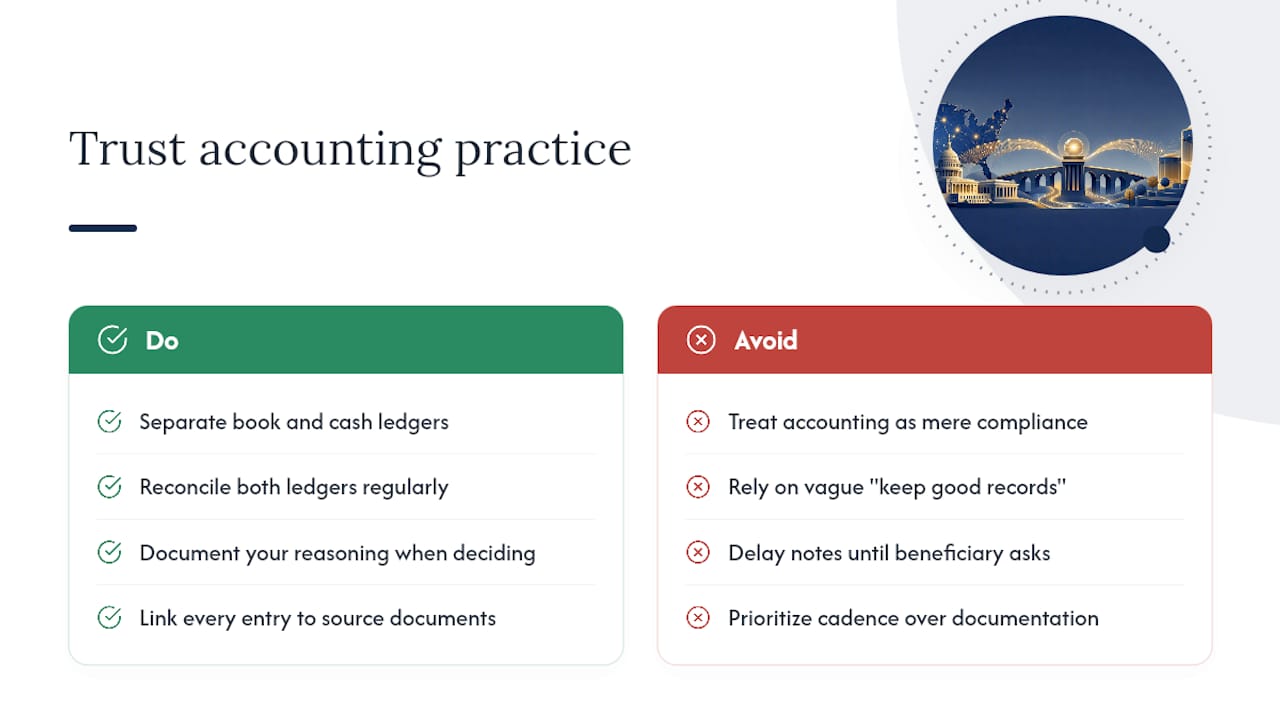
Private trustees face a smaller version of the same exposure. The conventional advice, “keep good records”, undersells what’s actually at stake. Good records don’t just protect you from an audit; they’re the only thing standing between a reasonable trustee decision and a lawsuit alleging breach of fiduciary duty. The reporting cadence matters less than most guides suggest. What matters is whether every entry ties back to a document and a documented rationale, months or years after you made the decision.
If you take one thing from federal trust fund practice and apply it to a family trust, take this: separate your book ledger from your cash ledger, reconcile both regularly, and write down your reasoning at the time you make a discretionary call, not after a beneficiary asks for one.
— Josh
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Social Security press release (2025)
- Federal Trust Fund & Accounting Guide | Bureau of the Fiscal Service


