

U.S. Social Security Insolvency 2032: Prepare for a 20–22% Cut
The Social Security Board of Trustees’ 2026 intermediate projection puts OASI trust fund depletion at the fourth quarter of 2032. Combined with disability insurance, the broader OASDI fund lasts until the third quarter of 2034, paying a substantial portion of scheduled benefits at that time. Social Security insolvency doesn’t mean checks stop. It means smaller checks, unless Congress changes the law first.
TL;DR:
- The Social Security trust fund that pays retirement benefits will deplete in the fourth quarter of 2032, reducing payments to about 83 percent unless reforms are made.
- Combining the retirement and disability funds to extend solvency beyond 2032 requires new legislation, which is not automatic.
- A 20 to 22 percent benefit reduction is likely if Congress takes no action, disproportionately hitting low-income retirees, widows, and those near retirement.
- Key reform options include raising payroll taxes, increasing the taxable wage cap, adjusting benefits, or delaying full retirement age, each with different trade-offs.
- Acting before 2032 lessens the need for sharp tax hikes or benefit cuts, emphasizing the importance of early individual financial planning.
Table of Contents
- Social Security Insolvency by the Numbers: The Timeline You Need
- What “Insolvency” Actually Means for Your Check
- Who Loses the Most If Congress Does Nothing
- Fixing Social Security: The Real Options on the Table
- Protecting Your Retirement from a Potential Benefit Cut
- History Suggests Congress Waits Until the Last Possible Moment
- Where to Verify These Numbers Yourself
- The Real Story Isn’t the Cut. It’s the Delay.
- Sources
Social Security Insolvency by the Numbers: The Timeline You Need
Three dates and three percentages tell you almost everything about where this stands right now. The Social Security Trustees’ 2026 report projects OASI, the fund that pays retirement and survivor benefits, runs dry in Q4 2032.
Here’s the mechanism behind those numbers. Social Security is funded by a 12.4% payroll tax split evenly between employers and employees, applied to wages up to a taxable maximum of $184,500 in 2026. That tax has not covered total program costs since 2010. The trust fund has been drawing down its reserves since 2021 to make up the difference.
| Metric | Figure |
|---|---|
| OASI depletion date | Q4 2032 |
| OASI benefits payable at depletion | 83% |
| Combined OASDI depletion date | Q3 2034 |
| Combined OASDI benefits payable at depletion | ~83% |
| 2026 payroll tax rate | 12.4% |
| 2026 taxable maximum | $184,500 |
| Long-range actuarial deficit | ~4.42% of taxable payroll |
The actuarial deficit is the number actuaries watch closest. The Congressional Research Service pegs the long-range OASDI shortfall at roughly 4.42% of taxable payroll, a figure that captures 75 years of projected imbalance in one metric. It’s also the number that determines how big any fix has to be, and it gets larger the longer Congress waits.
What “Insolvency” Actually Means for Your Check
“Insolvency” is a specific term with a specific mechanical meaning, and it’s worth separating from the more alarming picture people carry around in their heads. The trust fund holds reserves built up from decades of payroll tax surpluses, invested in special-issue Treasury securities. Every month, the Social Security Administration pays scheduled benefits by drawing on a mix of current payroll tax income and, when needed, those banked reserves.
Once reserves hit zero, the math changes. Federal law does not permit Social Security to borrow or pay benefits it cannot cover, so the agency would be legally limited to disbursing only what current payroll tax revenue brings in that month.
There’s a wrinkle most explainers skip. OASI and Disability Insurance are legally separate trust funds, each with its own balance sheet and its own depletion date. The Trustees’ report is explicit that combining them into a single OASDI account, which produces that later 2034 date and higher 83% figure, is not automatic. It requires Congress to pass a law authorizing the transfer. Absent that action, OASI hits its wall in 2032 on its own timeline, regardless of how healthy the Disability Insurance fund looks by comparison.
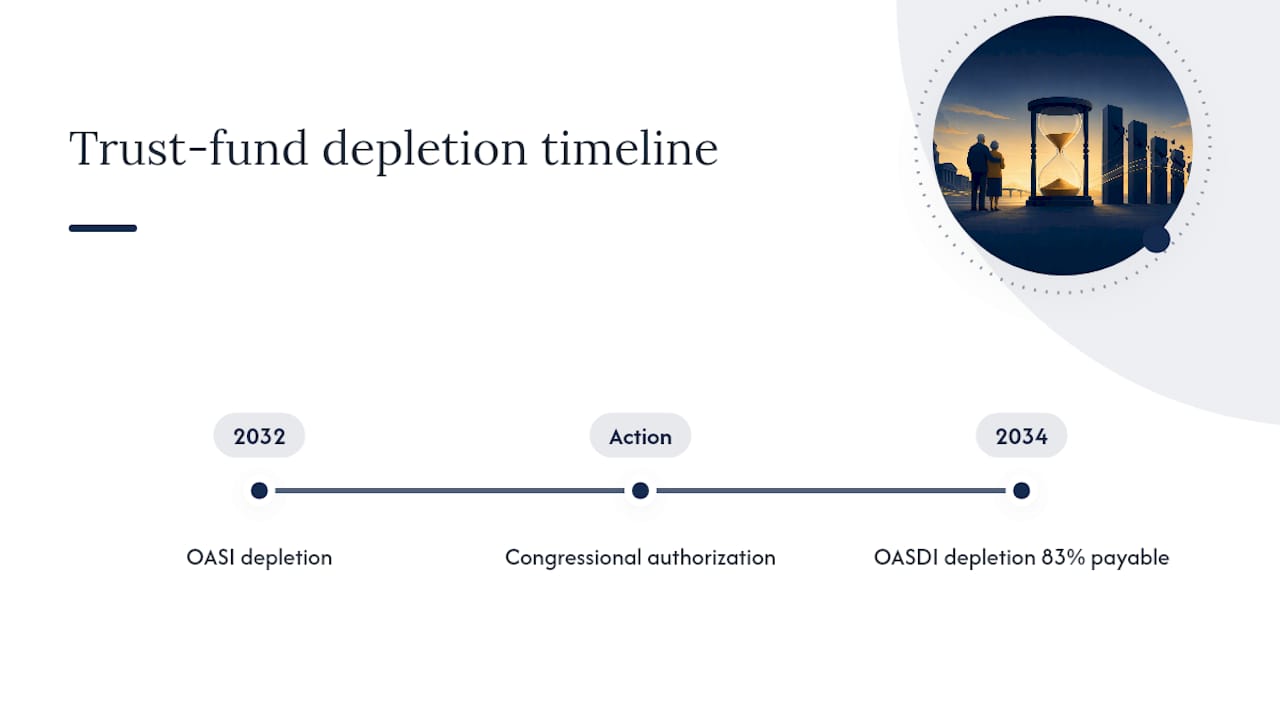
None of this touches the payroll tax itself or the benefit formula. Those require separate legislation entirely. Social security reform, in other words, isn’t one lever. It’s several, and Congress has to choose which ones to pull, and when.
Who Loses the Most If Congress Does Nothing
A flat percentage cut sounds abstract until you put it against a real budget. Social Security’s own actuaries and independent analysts estimate that under a pure no-action scenario, retirees would see something in the neighborhood of a 20 to 22% across-the-board reduction in scheduled benefits starting at depletion. For a retiree drawing an average benefit, that’s a significant shortfall that could affect covering essential expenses every month.
The cut hits everyone at the same percentage, but its consequences are wildly uneven. A retiree who depends on Social Security for most of their income absorbs the same cut as a threat to housing and food. Analysts tracking the distributional fallout expect measurable increases in senior poverty rates if the cut takes effect as currently projected, concentrated among people who have the least room to adjust.
Three groups carry disproportionate risk:
- Widows and surviving spouses, who often rely on a single, already-reduced survivor benefit with no second income to cushion a cut.
- Lower-income retirees, for whom Social Security represents the majority or entirety of retirement income, leaving little to reallocate.
- Near-retirees in their late 50s and early 60s, who have the least time left to rebuild savings or adjust their claiming strategy before the 2032 depletion date arrives.
Fixing Social Security: The Real Options on the Table
Congress has a limited menu of tools, and every one of them involves trade-offs that fall on different generations and income levels. None of them are secret. They show up in every serious reform proposal, and the debate is really about sequencing and size, not invention.
- Raise the payroll tax rate. Even a modest increase above the current 12.4% narrows the funding gap, though it raises costs for every working American immediately.
- Raise or eliminate the taxable maximum. Wages above $184,500 currently escape the payroll tax entirely. Because this targets higher earners, it’s one of the more politically durable options, and analysts note it echoes the tax base coverage the program had closer to the 1983 reform era.
- Adjust the benefit formula. Changing how the Primary Insurance Amount is calculated, or slowing cost-of-living adjustments, reduces outlays but directly lowers what future retirees receive.
- Raise the full retirement age. Effectively a benefit reduction spread over a longer working life, this shifts burden toward younger workers who have decades to adjust.
- Combine the OASI and DI trust funds. This alone doesn’t fix the underlying shortfall, but it buys time by pooling reserves, pushing the effective depletion date from 2032 to 2034.
- Tap general revenue or new borrowing. Politically contentious, since it breaks from the program’s self-funded design, but it’s a lever that exists.
The Trustees’ own reporting makes one point clearly: acting sooner shrinks the size of the fix. Spread a correction across more years and more birthdays, and the annual burden per worker drops. Wait until 2032, and the same fiscal gap has to be closed in a compressed window, which usually means a sharper tax increase or a steeper benefit cut than an earlier, phased approach would have required.
Pro Tip: Track legislative movement through the SSA’s official Trustees Report page and the Congressional Research Service’s public briefs rather than social media summaries. Bills that would meaningfully affect the taxable maximum or the retirement age tend to surface first in committee hearing schedules, not headlines.
Protecting Your Retirement from a Potential Benefit Cut
Start with what you can verify today.
- Pull your Social Security statement at ssa.gov and run the benefit estimator under different claiming ages. Seeing your own numbers, not averages, changes how you plan.
- Reconsider your claiming age. Delaying past full retirement age still increases your monthly benefit under current law, and a larger baseline benefit provides more cushion even if a future across-the-board cut reduces it proportionally.
- Stress-test your budget against a 20% cut. If losing a fifth of your projected Social Security income would break your monthly budget, that’s the gap to close now, not in 2032.
- Increase contributions to a 401(k) or IRA if you have room. Every dollar of non-Social Security retirement income is a dollar insulated from trust fund politics entirely.
- Build or maintain an emergency fund covering several months of expenses, since policy uncertainty around benefit timing adds a layer of risk retirees didn’t face a generation ago.
- Talk to a financial advisor with a specific question, not a vague one: “How does my retirement budget hold up if my Social Security benefit drops by 20% starting in 2032?” That framing forces a concrete answer instead of generic reassurance.
Pro Tip: If you’re within ten years of claiming, ask your advisor to model both the current-law benefit and the reduced-payable scenario side by side. Seeing the gap in dollar terms, not percentages, makes the planning decision far more concrete.
History Suggests Congress Waits Until the Last Possible Moment
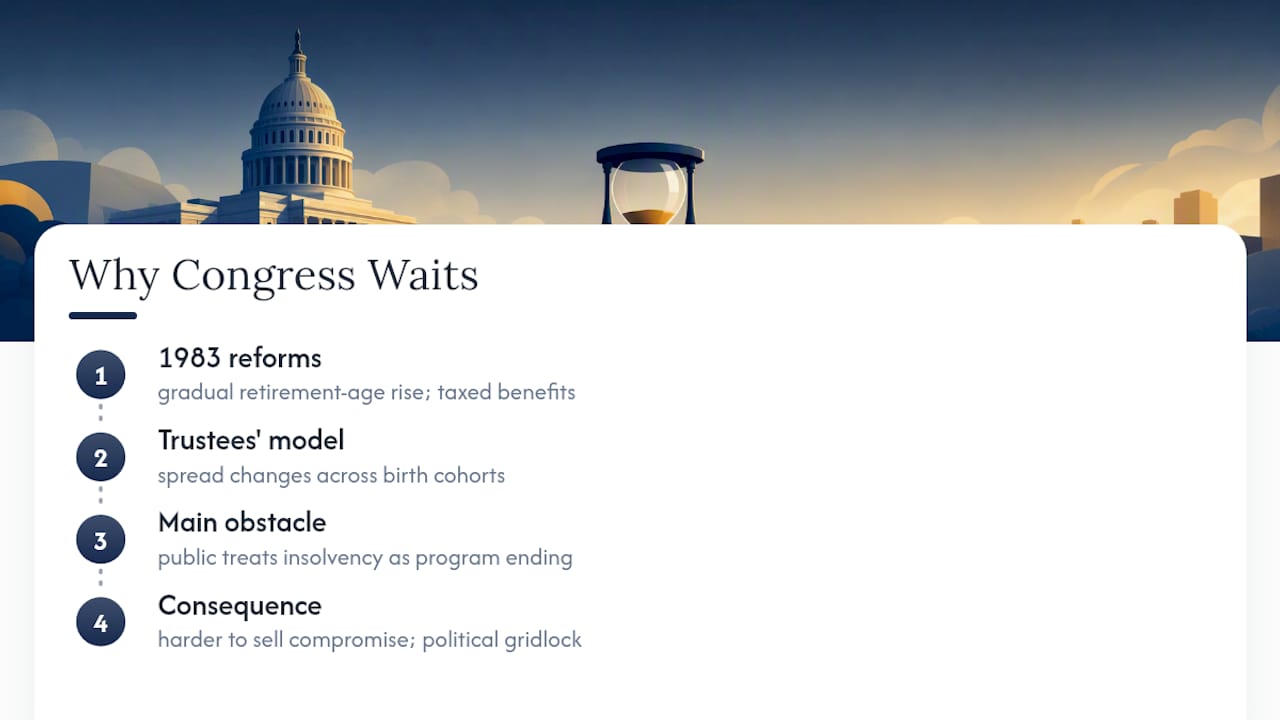
Congress has faced this before. The 1983 reforms, passed under a Reagan-era bipartisan deal, raised the retirement age gradually, taxed benefits for higher earners, and adjusted payroll tax timing, phasing changes in over decades rather than all at once. That’s the model the Trustees keep pointing back to: spread the adjustment across enough birth cohorts, and no single generation absorbs a shock.
The bigger obstacle now isn’t arithmetic. It’s communication. Research on public perception shows many Americans conflate “insolvency” with “the program disappearing,” which flattens a nuanced policy debate into fatalism and makes compromise harder to sell. Understanding the actual mechanics, reserves, payable percentages, statutory limits, is the first step toward evaluating any proposal on its merits. If you want the deeper political mechanics behind why reforms stall, Joshthinks breaks down the systemic pressures behind policy gridlock in a way that applies directly to entitlement reform.
Where to Verify These Numbers Yourself
Start with the SSA Trustees’ report summary for the depletion dates and payable percentages straight from the source, then read the CRS brief IF13256 for the actuarial deficit context. The Bipartisan Policy Center’s explainer breaks down policy trade-offs in plain language, and CNN’s coverage frames the political urgency for a general audience.
The Real Story Isn’t the Cut. It’s the Delay.
The Trustees’ numbers are clear enough that arguing over them wastes time better spent on the actual decision Congress keeps postponing. It’s what happens by default if nobody acts, which is a very different thing than a forecast of doom.
What gets underplayed in most coverage is how cheap this problem still is to solve today compared to solving it in 2033. The 1983 reforms worked precisely because lawmakers had years, not months, to phase changes in gradually. Every year of delay past 2026 shrinks that runway further and forces a choice between a bigger tax increase, a bigger benefit cut, or both landing on people with far less time to adjust.
If there’s one thing I’d tell readers to prioritize, it’s this: stop waiting for Washington’s timeline before you build your own. Fixing the country’s Social Security funding issues is Congress’s job. Fixing your exposure to the outcome is yours, starting well before 2032 arrives.
— Josh
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Trustees report summary (SSA)
- CRS: Social Security: Selected Findings of the 2026 Annual Report
- Bipartisan Policy Center — 2026 Trustees report explained
- CNN Politics: When could Social Security trust fund run out? Full benefits may not be paid in six years unless Congress acts


