

Role of Futures Exchanges in Price Discovery and Risk Management
Futures exchanges exist to do three things: set fair prices through open competition, let businesses transfer price risk to someone willing to take it, and turn standardized contracts into collateral firms can borrow against. That role helps a wheat farmer lock in a harvest price, lets an airline hedge jet fuel, and gives investors a liquid market to enter or exit. CME Group and the Chicago Board of Trade (CBOT) are the names most people already recognize, and for good reason. They built much of the infrastructure everyone else copied.
Key Takeaways
Futures exchanges function because standardized contracts and clearinghouse guarantees convert bilateral counterparty risk into a system anyone can trust and trade on.
| Point | Details |
|---|---|
| Three core roles | Futures exchanges enable price discovery, risk transfer, and access to capital through standardized, exchange-guaranteed contracts. |
| Clearinghouses eliminate counterparty risk | Novation makes the clearinghouse the buyer to every seller, backed by margin and guaranty funds. |
| Margin is a performance bond | Initial and variation margin settle daily, protecting the market without functioning as a loan or deposit. |
| Speculators supply liquidity | Research shows increased speculative activity often reduces volatility rather than causing it. |
| Major exchanges anchor different markets | CME Group, CBOT, NYMEX, ICE, and Cboe CFE each dominate specific contract categories. |
Table of Contents
- What Is a Futures Exchange and What Does It Actually Provide?
- What Are the Three Core Economic Roles of Futures Exchanges?
- How Do Standardized Contracts and Clearing Guarantee Performance?
- Who Trades on Futures Exchanges?
- What Happens Over the Life of a Futures Contract?
- Which Exchanges Dominate Futures Trading Today?
- How Are Futures Exchanges Regulated?
- What Are the Real Risks and Criticisms of Futures Trading?
- Why This Matters for How You Think About Risk
- Ready to Go Deeper Into Futures Markets?
- Frequently Asked Questions
- Sources
What Is a Futures Exchange and What Does It Actually Provide?
A futures exchange is an organized marketplace that creates standardized futures contracts and provides the venue, rules, and infrastructure to trade them safely. It is not just a place where buyers and sellers meet. It is a full operating system for a market: contract design, a trading venue, price reporting, a clearing function, and a rulebook that gets enforced when disputes arise.
The core services an exchange provides include:
- Contract specifications that fix size, quality grade, delivery month, and location so every buyer knows exactly what they’re getting.
- A trading venue, whether electronic order-matching systems or the diminishing pockets of open-outcry pit trading.
- Market data distributed in real time so prices are visible to everyone, not just insiders.
- A clearinghouse that guarantees both sides of every trade.
- Margining rules that require collateral before and during a position.
- A rulebook and arbitration process for resolving disputes between members.
Compare that to a forward contract negotiated directly between two parties over the counter. A forward carries bilateral credit risk. If your counterparty goes bankrupt, you’re standing in line with other creditors. A futures contract, by contrast, is standardized down to the delivery grade and settled daily through mark-to-market accounting, with the exchange’s clearinghouse absorbing the default risk instead of you. That single structural difference is why futures markets scaled into trillion-dollar daily volumes while most forward markets stayed relationship-based and comparatively thin.
What Are the Three Core Economic Roles of Futures Exchanges?
Strip away the mechanics and futures exchanges perform three jobs, according to the CFTC’s own explanation of economic purpose: price discovery, risk transfer, and facilitating access to capital.
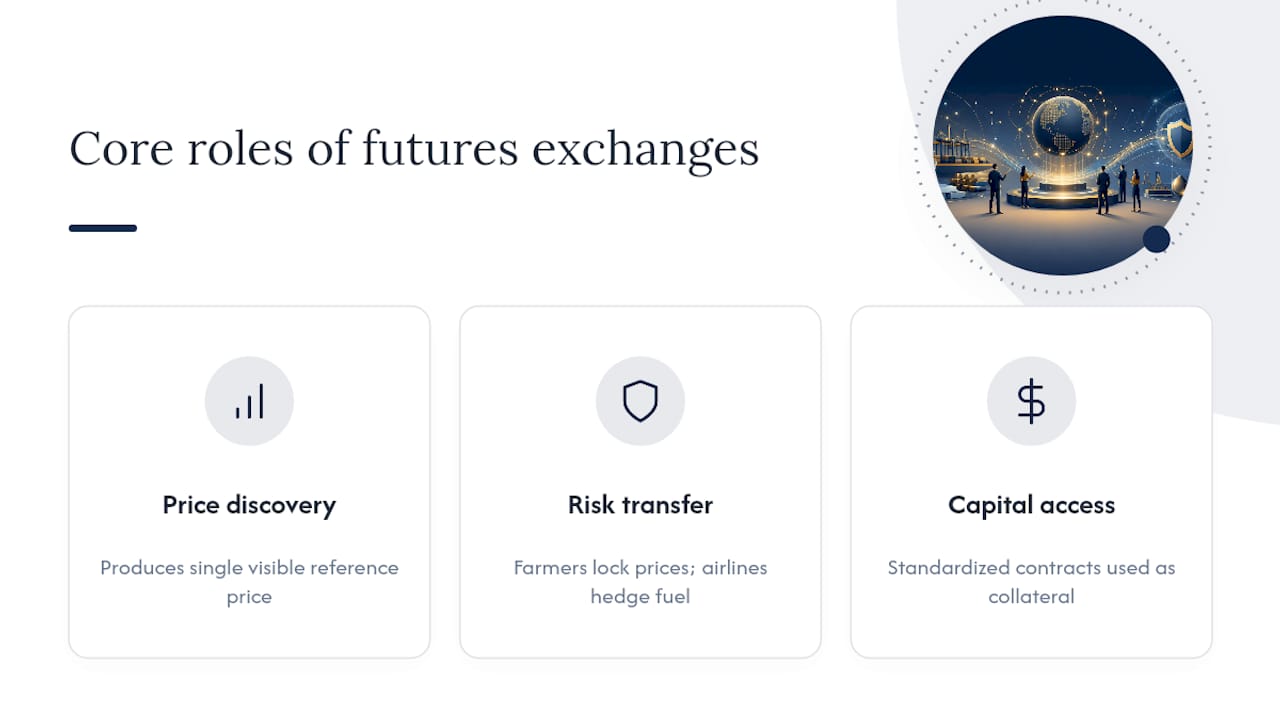
Price discovery happens because concentrated trading in one venue produces a single, visible reference price. When corn futures trade on the CBOT, that price becomes the number grain elevators, exporters, and food manufacturers around the world reference, a function documented back to the earliest organized U.S. futures markets.
Risk transfer is the hedging function. An Iowa corn farmer sells futures to lock in a harvest price months before the crop comes out of the ground; an airline buys fuel futures to protect its margins against a spike in oil.
Access to capital is the least understood role. Because futures contracts are standardized and exchange-guaranteed, they make efficient collateral. That practical function traces back to 19th-century Chicago grain dealers, who used early futures instruments to secure credit for inventory they hadn’t yet sold. The same logic underpins commodity finance today.
How Do Standardized Contracts and Clearing Guarantee Performance?
Here’s the mechanical flow that makes a futures trade safe enough for a stranger on one side of the world to trade with a stranger on the other: a trade gets executed, a clearing member submits it, and the clearinghouse steps in through a process called novation. It becomes the buyer to every seller and the seller to every buyer. Neither side ever needs to trust the other directly.
- Trade execution happens electronically or, on a shrinking number of contracts, in open outcry pits.
- Novation replaces the original counterparty with the clearinghouse itself.
- Initial margin gets posted before the position opens, sized to cover a worst-case one or two-day price move.
- Variation margin settles daily, crediting or debiting accounts based on that day’s price change.
- Expiry ends in either cash settlement or physical delivery, depending on the contract.
Margin confuses a lot of newcomers because it sounds like a down payment. It isn’t. It’s a performance bond, collected to guarantee you’ll cover your losses, not to buy a portion of the asset. That’s why margin can be a small fraction of the total contract value and still provide serious credit protection: the daily settlement process never lets losses accumulate for long before they’re collected.
Behind that daily cycle sits a guaranty fund, a pool of capital clearing members contribute to that the clearinghouse can tap if a member defaults and its margin isn’t enough to cover the loss. Exchanges run daily stress tests to size these buffers realistically rather than guess at them.
Pro Tip: If you ever see a contract labeled “cash settled” versus “physically settled,” check which one before you hold a position into expiry. Physical delivery contracts can require you to accept or deliver an actual commodity if you don’t close out in time, which is rarely what a retail trader wants.
Margin calculation methods vary by exchange too. Many commodity markets use SPAN, a grid-simulation model; some options-clearing operations use STANS instead. The two approaches produce different initial margin outcomes for economically similar positions, which is worth knowing if you ever compare margin requirements across venues.
Who Trades on Futures Exchanges?
Hedgers are the reason the market exists in an economic sense. Producers, processors, and end users use futures to lock in prices and reduce uncertainty in their underlying business.
Speculators take on the price risk hedgers want to shed, and in doing so, they supply much of the market’s liquidity. Prop trading firms, hedge funds, and market makers each play a distinct role here. CME Group’s own education material on speculators describes them as essential counterparties, not bystanders.
Arbitrageurs exploit small pricing gaps between related contracts, which keeps prices consistent across venues and maturities. Brokers and clearing members handle order routing and guarantee client positions to the exchange.
The CFTC publishes weekly Commitments of Traders reports breaking down positions by category, and exchanges enforce position limits to prevent any single trader from dominating a market.
Pro Tip: Reading a Commitments of Traders report takes five minutes and tells you whether commercial hedgers or speculative funds are driving recent price moves in a given contract, information most retail traders never bother to check.
What Happens Over the Life of a Futures Contract?
A contract’s life follows a predictable path:
- Listing. The exchange introduces a new contract month with fixed specifications.
- Trading. Orders match electronically (or, occasionally, in an open-outcry pit) as the contract accumulates volume.
- Daily margining. Gains and losses settle each day through variation margin.
- Rolling. Traders who want to keep a position but avoid delivery close the expiring contract and open the next month out.
- Expiry and settlement. The contract settles in cash or through physical delivery of the underlying asset.
Two terms come up constantly around this cycle: contango, when futures prices sit above the expected spot price, and backwardation, when they sit below it. Both shape whether rolling a position costs you money or pays you, which matters enormously to anyone holding a futures-based position for more than a few weeks.
Which Exchanges Dominate Futures Trading Today?
CME Group is the largest U.S. futures operator and now owns the Chicago Board of Trade (CBOT) and the New York Mercantile Exchange (NYMEX), covering everything from E-mini S&P 500 futures and Treasury contracts to corn, soybeans, and WTI crude oil.
Intercontinental Exchange (ICE) built its footprint in energy and later expanded into a broad range of financial and agricultural products, including Brent crude, a global benchmark for oil pricing.
Cboe Futures Exchange (CFE) is best known for VIX futures, the volatility contract tied to the S&P 500 options market.
Each exchange publishes full contract specifications on its own site, and that’s the first place to check before trading anything you haven’t used before. Not every contract an exchange launches survives; only the ones that meet real hedging or speculative demand stay liquid over time.
How Are Futures Exchanges Regulated?
In the United States, the Commodity Futures Trading Commission (CFTC) oversees market integrity, requires clearinghouses to meet capital and risk standards, and reviews new contract listings. Exchanges also self-regulate: CME Group, ICE, and CFE each run their own market surveillance and enforcement teams that monitor trading in real time.
Oversight functions include:
- Position limits that cap how large a single trader’s holdings can grow.
- Large-trader reporting that flags concentrated positions before they become systemic risks.
- Clearinghouse standards covering capital adequacy and default management.
- Market surveillance for manipulation, spoofing, and disorderly trading.
Regulatory frameworks differ outside the U.S., but the same basic layering, exchange self-regulation backed by a government regulator, shows up in most developed futures markets. Legislative activity around adjacent financial infrastructure, like the U.S. Senate’s recent work on stablecoin regulation, signals how oversight regimes keep expanding to cover new forms of financial risk.
What Are the Real Risks and Criticisms of Futures Trading?
Leverage is the biggest one. Because margin is a fraction of contract value, losses can outpace what a trader initially put up, triggering a margin call that demands more cash fast. Liquidity can dry up in thin contracts during stress, and concentrated positions occasionally raise manipulation concerns.
Speculators draw the most criticism, often blamed for price spikes in food or energy markets. The evidence doesn’t back that up cleanly. A CFTC study using detailed trader-position data found that increased speculative activity generally does not cause price changes and, in several commodity markets, actually correlated with reduced volatility.
Pro Tip: Before assuming a price spike is “speculator-driven,” check whether commercial hedging demand shifted first. Speculators tend to follow price signals, not create them.
Exchanges mitigate these risks with daily margining, position limits, guaranty funds, and regular stress testing, the same infrastructure that turned a 19th-century grain-trading problem into a global risk-management tool.
Why This Matters for How You Think About Risk
Understanding these mechanics changes how you evaluate any investment tied to commodities or rates. Once you see how margin, clearing, and liquidity actually interact, price swings stop looking random. If you want the deeper mechanics of how contracts fit into an actual portfolio, our investor’s guide to financial futures walks through it.
Ready to Go Deeper Into Futures Markets?
Everything above covers the institutional plumbing. Applying it to your own decisions is a different skill, one that gets built through examples, not definitions. Joshthinks’ investor’s guide to financial futures breaks down contract types and portfolio use cases in plain language, and if you’re specifically curious about smaller-scale contracts, our practical walkthrough on trading MES futures covers what actually trips up new traders. Both build directly on the framework in this article.
Frequently Asked Questions
What is the main role of futures exchanges in financial markets?
The primary role of futures exchanges is threefold: they enable price discovery through transparent, competitive trading, they let businesses transfer price risk to willing speculators, and they let standardized contracts function as efficient collateral for financing.
How do futures exchanges make trading safer than direct forward contracts?
Futures exchanges use a clearinghouse that becomes the counterparty to every trade through novation, plus daily mark-to-market margining, which eliminates the bilateral credit risk that exists in privately negotiated forward contracts.
Why are speculators important to futures markets?
Speculators absorb the price risk hedgers want to offload and, in doing so, supply the liquidity that lets hedgers find counterparties quickly. Studies from the CFTC suggest their activity generally doesn’t drive price changes and can reduce volatility.
What is the difference between CME Group, ICE, and Cboe Futures Exchange?
CME Group owns CBOT and NYMEX and dominates U.S. financial, agricultural, and energy futures. ICE built its base in energy and expanded into financial and agricultural products globally. Cboe Futures Exchange specializes in volatility products like VIX futures.
Who regulates futures exchanges in the United States?
The Commodity Futures Trading Commission (CFTC) oversees U.S. futures exchanges, working alongside exchange self-regulation programs that handle day-to-day market surveillance, position limits, and rule enforcement.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Economic Purpose of Futures Markets and How They Work — CFTC
- Introduction to futures markets — Texas A&M (myTexas)
- Eh
- Understanding the role of speculators — CME Group education


