

Commitment of Traders Report: How to Read COT Data
The Commitments of Traders (COT) report is a weekly breakdown of who holds what in U.S. futures markets, split into trader categories like commercial hedgers, large speculators, and small traders. The CFTC publishes it using a snapshot taken every Tuesday, then releases the actual report every Friday at 3:30 p.m. Eastern Time. That three-day lag matters, and we’ll get to why.
For now, here’s what to do with that information:
- Open the CFTC’s COT index page and find a market you actually trade.
- Pull up a COT chart (Barchart and CME Group both have free ones) for that same market before you read another word of this article.
Quick fact: the report format you choose changes what you see entirely. A gold trader reading the Legacy report misses the swap dealer detail sitting one click away in the Disaggregated version.
Key Takeaways
The COT report turns raw futures positioning into a usable sentiment tool only when paired with the correct report format, a properly built COT Index, and confirmation from price action.
| Point | Details |
|---|---|
| Match format to market | Use Disaggregated for commodities and TFF for financial futures instead of defaulting to Legacy. |
| Build a real COT Index | Normalize net position against its own historical high and low, not just the raw contract count. |
| Respect the release lag | Data reflects Tuesday’s positioning but publishes Friday at 3:30 p.m. ET, so fast markets can already have moved. |
| Confirm before acting | Pair positioning extremes with price trend and volume before treating them as a signal. |
| Know the coverage gap | Reportable positions cover a substantial majority of open interest, leaving nonreportable as a residual estimate. |
Ready to put positioning data to work in an actual strategy? This walkthrough on trading MES futures covers the execution and risk-management side that COT analysis alone won’t teach you, and the broader Finance & Markets section at Joshthinks keeps building on both.
Table of Contents
- What Is a Commitment of Traders Report, Exactly?
- Who Are the Traders in the COT Report?
- How Do You Read COT Data Like a Trader?
- Where Can You Find COT Charts and Data Tools?
- What Do Real COT Signals Look Like in Practice?
- What Are the Limitations of the COT Report?
- What matters most before you trust a COT signal
- Where to Find the Official COT Data and Charts
- Sources
What Is a Commitment of Traders Report, Exactly?
The COT report isn’t one document. It’s four different formats, each slicing the same open interest data by different trader groups, and picking the wrong one means missing the categories that actually matter for your market.
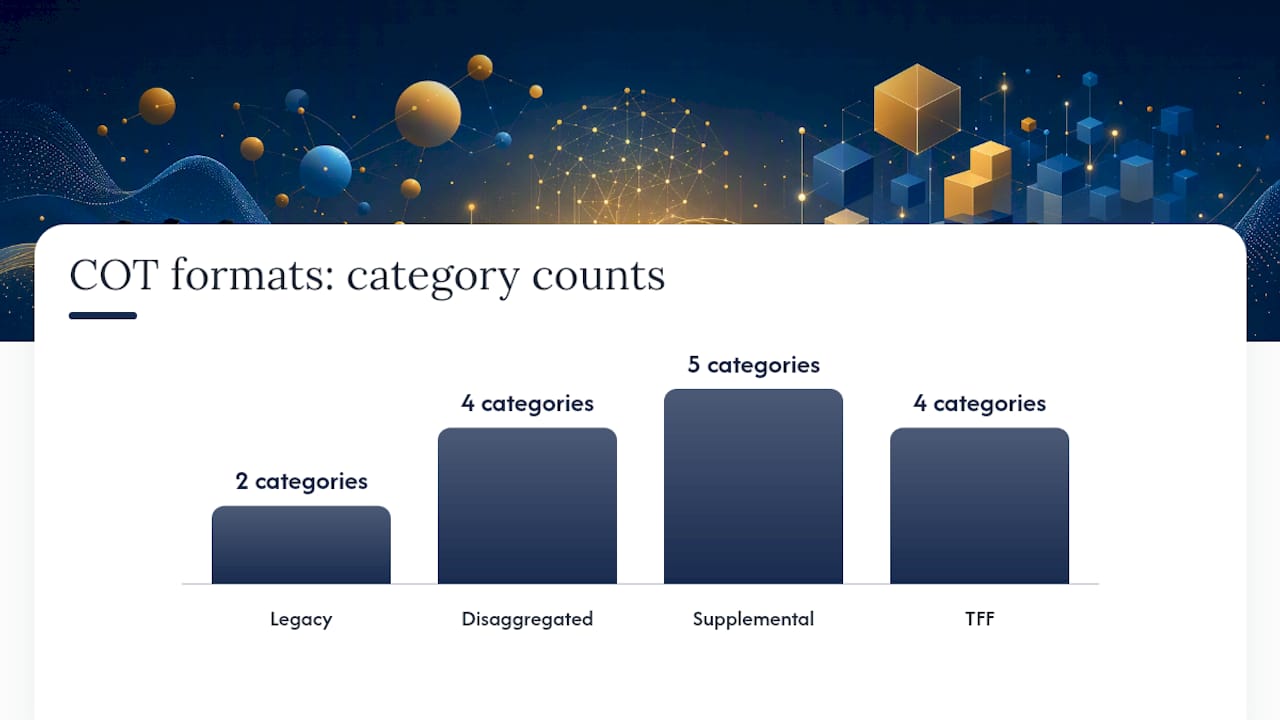
The CFTC breaks these out as Legacy, Disaggregated, Supplemental, and Traders in Financial Futures (TFF). Each comes in a “short” and “long” version, and the long format adds crop-year groupings plus concentration ratios showing what percentage of open interest the four and eight largest traders control.
Here’s how the four formats break down:
- Legacy: The original format, splitting traders into just commercial and non-commercial. Works fine for a quick read but hides a lot of nuance in physical commodity markets.
- Disaggregated: Covers physical commodities (grains, energy, metals) and splits traders into Producer/Merchant/Processor/User, Swap Dealers, Managed Money, and Other Reportables. This is the format most commodity traders actually want.
- Supplemental: Adds an “Index Traders” category for select agricultural markets. It is useful for spotting commodity index fund flows separate from other speculative activity.
- TFF: Built for financial futures like currencies, interest rates, and stock indices. Splits participants into Dealer/Intermediary, Asset Manager/Institutional, Leveraged Funds, and Other Reportables.
Every version shows the same core columns: long positions, short positions, spreading (positions that are both long and short simultaneously, common among spread traders), and each category’s percent of total open interest. Week-to-week changes get their own column too, which is where a lot of the useful signal actually lives.
If you trade corn or soybeans, you want Disaggregated. If you trade the 10-Year Treasury or the Euro, TFF is your report. Using Legacy for either works, technically, but you’re reading a blurrier picture than you need to.
Who Are the Traders in the COT Report?
Classification is where most COT confusion starts, mostly because “commercial” doesn’t mean what people assume it means.
In the Legacy report, traders fall into three buckets: commercial (entities using futures to hedge actual business risk, like a wheat farmer locking in a price), non-commercial (large speculators, funds, and money managers betting on price direction), and nonreportable (everyone below the CFTC’s reporting threshold, mostly retail traders and small accounts).
The Disaggregated report gets more specific for physical commodity markets:
- Producer/Merchant/Processor/User: The actual commercial players hedging physical exposure.
- Swap Dealers: Banks and institutions managing swap-related risk, often on behalf of clients rather than for directional bets.
- Managed Money: Hedge funds, CTAs, and other professional speculators. This is the group most traders watch for sentiment extremes.
- Other Reportables: Large traders that don’t fit neatly elsewhere.
TFF mirrors this idea for financial futures with Dealer/Intermediary, Asset Manager/Institutional, and Leveraged Funds standing in for the physical-market categories.
Why does this matter beyond trivia? A “commercial” label doesn’t guarantee pure hedging intent. Swap dealers sometimes carry directional exposure passed through from client positions, and a swap dealer showing a large net-short doesn’t necessarily mean anyone is bearish on the commodity itself.
Pro Tip: Before treating any category’s positioning as a sentiment signal, check which report format you’re using. “Commercial net-long” in Legacy format can mean something completely different than “Producer/Merchant net-long” in Disaggregated, because the underlying trader pool isn’t the same.
How Do You Read COT Data Like a Trader?
Raw COT numbers mean nothing until you turn them into a comparison. Here’s the actual process traders use:
- Calculate net position. Subtract shorts from longs for each category. A Managed Money group holding 80,000 long contracts and 20,000 short contracts has a net long of 60,000. That single number is more useful than the two raw figures.
- Convert to percent of open interest. A net long of 60,000 contracts means very different things in a market with 200,000 total open interest versus one with 2 million. Dividing net position by total open interest normalizes this across markets and time.
- Check concentration ratios. The largest four and eight traders’ share of open interest, included in the long-format reports, tells you how much of the market a handful of players control. High concentration in a thin market amplifies the risk of a positioning unwind.
- Build a simple COT Index. Take the current net position, then find where it sits relative to its own high and low over a lookback period, usually one to three years. The formula: (current net position minus the period’s lowest net position) divided by (the period’s highest minus lowest), multiplied by 100. A reading above 90 means positioning is near a multi-year extreme; below 10 means the opposite.
- Track week-to-week change, not just the level. A Managed Money group that’s been net long for six months but is now unwinding fast tells a different story than one that just got there.
The heuristics that experienced traders lean on tend to repeat across markets. Extreme net positioning in the small speculator or nonreportable category is often read as a contrarian flag, since retail positioning tends to cluster near turning points rather than ahead of them. Commercial positioning gets read as the hedging side of the ledger, meaning heavy commercial shorts in a rallying market can reflect producers locking in favorable prices rather than a bearish call on direction.
None of this works in isolation. A COT Index reading of 95 on its own is a data point, not a trade signal, until price action either confirms or contradicts what the positioning implies.
Where Can You Find COT Charts and Data Tools?
You don’t need to build spreadsheets from scratch to use this data well. A handful of sources cover almost everything a retail trader needs.
The CFTC’s Public Reporting Environment is the primary source and includes an API along with searchable, filterable downloads. Historical compressed files go back further than most people expect: Futures-Only data to 1986, Options-and-Futures-Combined to 1995, and Supplemental data to 2006. If you want to backtest a COT Index against years of price data, this is where the raw material lives.
CME Group’s interactive COT tool sits on top of that same CFTC data with configurable charts, including disaggregated and non-reportable breakouts, plus a user guide that walks through every feature. It’s built for CME-listed products specifically, which makes it the fastest path if you trade grains, energy, or interest rate futures on that exchange.
Barchart’s COT charts update weekly and add a friendlier visualization layer with market groupings, useful if you want a fast visual scan across several markets without digging through raw tables. Myfxbook offers a similar service geared toward forex traders, translating TFF data into currency-specific sentiment views.
| Source | Best For | Update Cadence |
|---|---|---|
| CFTC Public Reporting Environment | Raw data, API access, historical backtesting | Weekly, Friday 3:30 p.m. ET |
| CME Group COT tool | Exchange-specific charting with disaggregated views | Weekly |
| Barchart | Fast visual reads across multiple markets | Weekly |
| Myfxbook | Forex-focused sentiment views from TFF data | Weekly |
If you’re building your own COT Index rather than relying on a charting tool, you need three columns at minimum: the date, the net position for your category of interest, and total open interest. The most common mistake is mixing report formats mid-series, pulling Legacy data for some weeks and Disaggregated for others, which quietly corrupts the whole index.
What Do Real COT Signals Look Like in Practice?
Positioning extremes only matter once you see how they play out in an actual market, not just in the abstract.
- Grain markets and managed money extremes. Say Managed Money’s net-short position in corn hits a three-year low on the COT Index, meaning funds are about as bearish as they’ve been in years. That alone isn’t a buy signal. The confirmation traders look for is a slowdown in the pace of new shorts being added week-over-week, combined with price stabilizing or forming a base despite the still-bearish positioning. Extreme positioning with decelerating momentum is a very different setup than extreme positioning still accelerating.
- Gold and the commercial hedger read. When commercials show a growing net-long in gold while price keeps drifting lower, that divergence is worth flagging. Producers and merchants aren’t usually adding hedges into weakness for no reason. It doesn’t mean a reversal is imminent, but it’s the kind of signal traders pair with technical support levels or a shift in real yields before acting on it.
- Combining COT with trend and momentum. The single biggest improvement to COT-based analysis is refusing to trade positioning extremes against a strong trend. A COT Index at 95 in a market making new highs on strong momentum has historically been less reliable as a reversal signal than the same reading after price has already stalled.
Pro Tip: Treat any single-week COT extreme as a question, not an answer. Pull up a price chart alongside your COT Index and check whether volume or open interest is confirming the same story before you size a position around it.
If you’re new to how futures pricing and settlement actually work underneath these positioning numbers, this guide to financial futures fills in that mechanical layer.
What Are the Limitations of the COT Report?
The COT report is a genuinely useful tool with real blind spots, and ignoring them is how traders overreact to noise.
- The Tuesday-to-Friday lag means fast-moving markets can shift meaningfully before the data even publishes, so a report can already be stale for short-term traders by the time they read it.
- “Commercial” classification doesn’t guarantee pure hedging intent. Swap dealers and even some commercial accounts carry positions with mixed motivations.
- Coverage is partial. Reportable positions usually account for a substantial majority of open interest depending on the market, and the nonreportable category is simply what’s left over, not a precisely measured group.
- A single week’s move in any category is weak evidence on its own. Traders who chase one anomalous data point without multi-week confirmation get burned more often than not.
The report tells you positioning. It doesn’t tell you why, and it never tells you what happens next with certainty.
What matters most before you trust a COT signal
The COT report earns its reputation because it’s the only publicly available window into how professional money is actually positioned, not just how it talks about positioning in interviews or research notes.
Where I think most explainers get it wrong is treating the COT Index like a standalone oscillator, the way you’d read RSI. It isn’t. A reading of 95 tells you positioning is stretched relative to its own history, and that’s genuinely useful, but stretched positioning in a strong trend has historically behaved nothing like stretched positioning in a stalling market. The number needs a second data point before it means anything.
The other overlooked issue is format selection. Traders default to whatever report loads first instead of matching the format to the market. If you trade grains and you’re still reading Legacy-format commercial data instead of the Disaggregated breakout, you’re working with a blurrier picture than the data actually offers.
Start with the right report format, build your own index instead of trusting someone else’s chart blindly, and always ask what price is doing before you act on a positioning extreme.
— Josh
Where to Find the Official COT Data and Charts
- CFTC: full reports, explanatory notes, and API access through the Public Reporting Environment.
- CME Group: interactive charting tool with a full user guide.
- Barchart: weekly-updated COT charts with market group filters.
- Myfxbook: forex-specific sentiment views built from TFF data.
- For context on how positioning shifts ripple into broader capital flows, this commentary on gold and Bitcoin ETF flows is worth a look.


