

2026 U.S. Social Security COLA: 2.8% Means About $56 More a Month
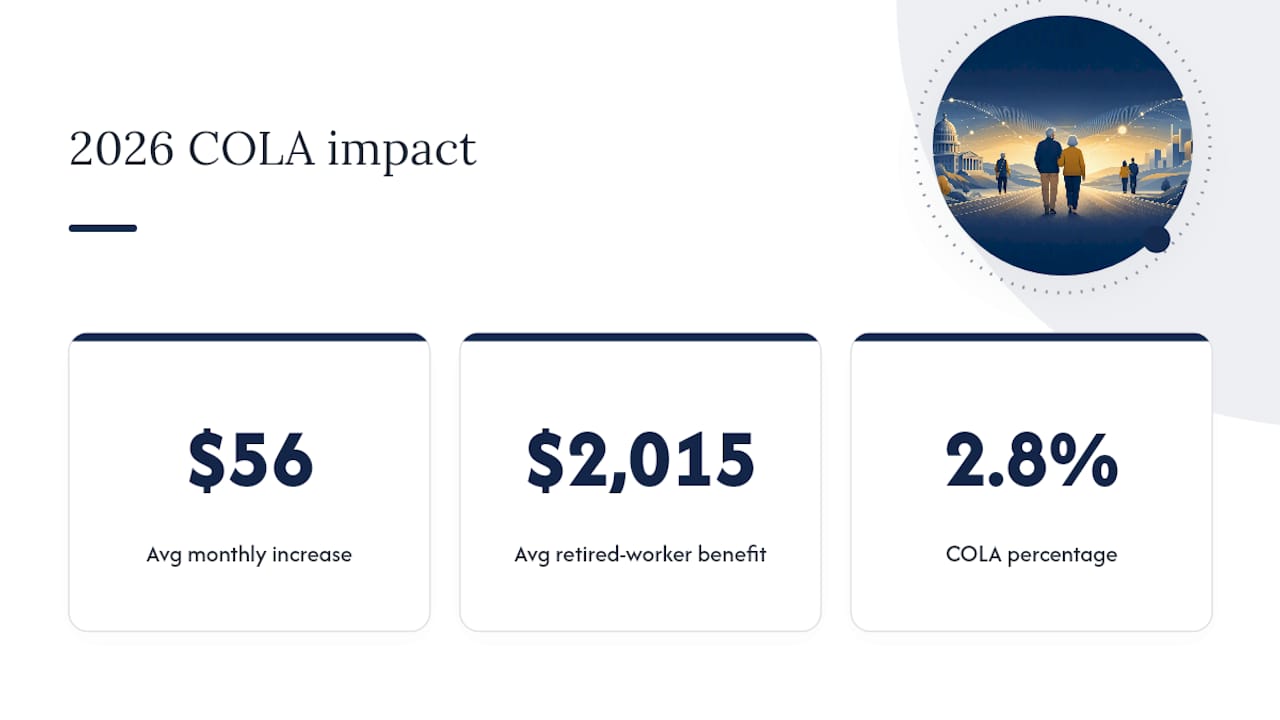
Social Security benefits are rising 2.8% for 2026, with the increase showing up in checks paid in January 2026 (for December 2025 benefits) and in SSI payments starting December 31, 2025. On average, retired workers will see about $56 more per month. The Social Security Administration confirmed both figures directly.
TL;DR:
- The 2.8% COLA for 2026 will increase most Social Security and SSI benefits starting in late December 2025 and January 2026, respectively.
- Medicare Part B premiums are deducted from benefits and may reduce the net increase, especially if premiums rise in the same year as the COLA.
- The average benefit increase for retirees will be about $56 per month, but actual gains depend on individual benefits and tax situations.
- The COLA calculation is based on third-quarter CPI-W data, and the official announcement comes from the SSA in October each year.
- Beneficiaries should verify their personalized increase via their online Social Security account and plan for potential adjustments to taxes or deductions.
Table of Contents
- What Is the 2026 Social Security COLA and Who Gets It?
- How Is the Social Security COLA Calculated?
- How Much More Will You Actually Get in 2026?
- When Does the SSI Increase Start, and Why Is It Different?
- Why Your Real Increase Might Feel Smaller Than 2.8%
- How Does the 2026 COLA Compare to Past Years?
- When Will the 2027 COLA Be Announced?
- How Do You Confirm Your Own COLA Notice and Plan Around It?
- What the 2026 COLA Really Means for Your Long-Term Plan
- Where to Go Next If You Want to Protect More of Your Income
- Sources
What Is the 2026 Social Security COLA and Who Gets It?
The Social Security Administration made it official on October 24, 2025: a 2.8% cost-of-living adjustment for 2026. That single number touches nearly every corner of the Social Security system, and the agency estimates it affects roughly 75 million people nationwide, according to its own press release.
Here’s who’s covered and how to confirm your own number:
- OASDI programs — retirement, survivors, and disability benefits — all get the 2.8% bump.
- SSI (Supplemental Security Income) recipients get the same percentage increase, just on a different calendar.
- A very large number of people receive Social Security benefits, and many more receive SSI benefits, according to SSA’s count.
- The fastest way to see your personal number is your my Social Security account, not a phone call or a guess based on last year’s letter.
If you haven’t logged into your account in a while, now is the moment. Your Message Center often shows the new figure before the paper notice lands in your mailbox.
How Is the Social Security COLA Calculated?
The COLA isn’t a political decision or a budget negotiation. It’s arithmetic, dictated by law, and it runs through the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W), a Bureau of Labor Statistics index that tracks what working households pay for everyday goods.
Here’s the process, step by step:
- SSA takes the average CPI-W for the third quarter (July, August, September) of the current year.
- That average gets compared to the CPI-W average from the third quarter of the last year a COLA was applied.
- The percentage difference is rounded to the nearest tenth of a percent, which is where 2.8% comes from for 2026.
- If prices didn’t rise enough during that window (or fell), the rounded result can hit zero. That’s happened before, and when it does, there’s simply no COLA that year.
The Bureau of Labor Statistics owns the data collection; SSA owns the math. Neither agency has discretion to adjust the outcome once the third-quarter numbers are in, which is why the COLA calculation is one of the more predictable pieces of an otherwise complicated system.
How Much More Will You Actually Get in 2026?
A percentage doesn’t mean much until it’s translated into your specific check, and here’s where the math gets personal. The 2.8% applies to your individual base benefit, so two retirees with different work histories will see different dollar amounts even though the percentage is identical.
SSA’s own fact sheet lays out the average effect across common beneficiary categories:
Pro Tip: These are averages, not your number. If your benefit runs higher or lower than the average retired worker’s $2,015, your dollar increase will scale accordingly, even though the percentage stays fixed at 2.8%.
The SSA’s headline statistic is that retirement benefits rise by about $56 a month on average. Someone with a smaller benefit checks in below that; someone with a larger one clears it easily.
When Does the SSI Increase Start, and Why Is It Different?
SSI runs on a slightly different clock than retirement and disability benefits, and the reason is almost comically simple: January 1 falls on a holiday, so SSA moves the payment earlier.
- SSI’s 2.8% increase takes effect December 31, 2025, not January 2026 like OASDI benefits.
- Don’t mistake that early December deposit for a bonus. It’s your January payment, just arriving ahead of schedule because of the New Year’s holiday.
- New federal payment standards for SSI individuals and couples are listed on SSA’s 2026 fact sheet, and your updated amount will also show in your online account.
Retirees who split income between OASDI and SSI sometimes get confused seeing two different effective dates on the same COLA. The percentage is identical. Only the calendar shifts.
Why Your Real Increase Might Feel Smaller Than 2.8%
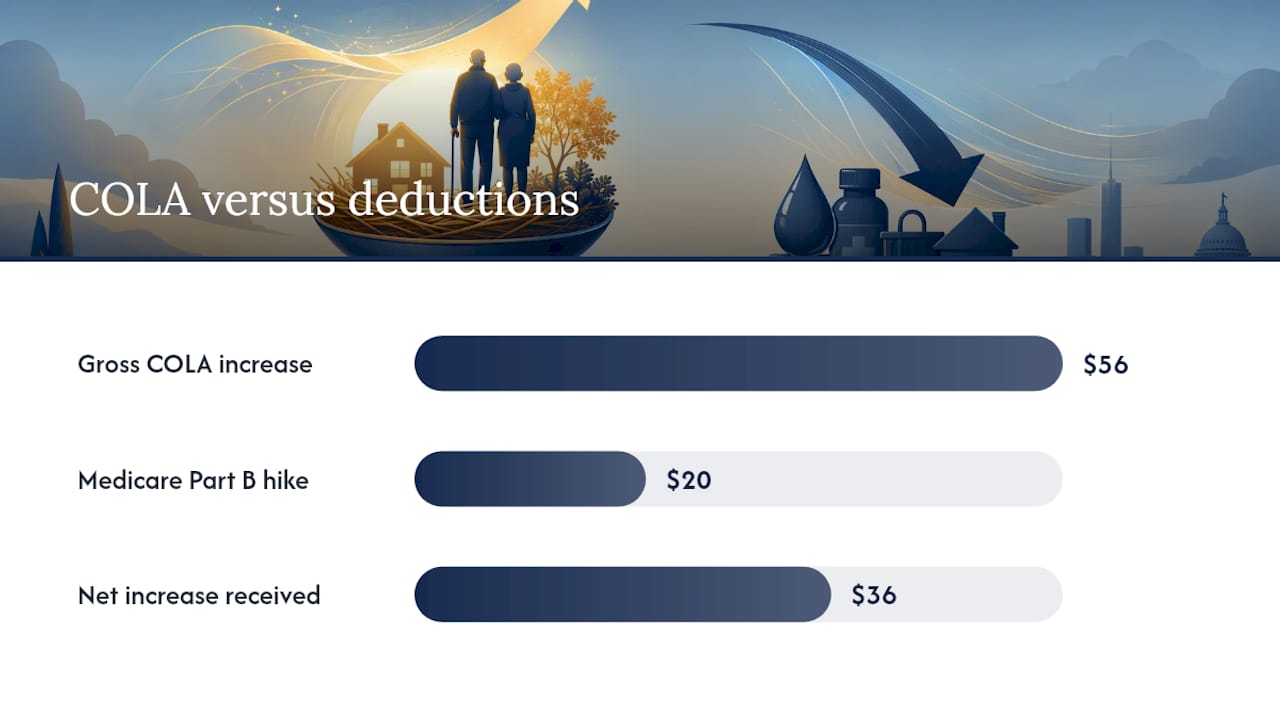
Here’s the part that catches a lot of retirees off guard every year: the 2.8% is calculated on your gross benefit, but what lands in your bank account depends on what gets deducted first. Medicare Part B premiums come straight out of most Social Security checks, and when those premiums climb in the same year as a COLA, they eat into the raise before you ever see it.
Say your gross benefit rises by $56. If your Part B premium jumps by $20 that same year, your net increase is really $36, not $56. On top of that, higher-income beneficiaries may owe federal tax on a portion of their benefits, which trims things further depending on total household income.
Pro Tip: Check Medicare.gov or your Medicare Summary Notice each fall for the coming year’s Part B premium before you assume your full COLA is spendable cash.
How Does the 2026 COLA Compare to Past Years?
Context helps here. Some years bring modest bumps; a few bring nothing at all.
Over the past decade, COLAs have averaged around 3.1%, which puts 2026’s 2.8% slightly below that recent norm but far ahead of the zero years that followed the 2008 financial crisis. The full historical table lives on SSA’s COLA page if you want to trace every year back to 1975.
When Will the 2027 COLA Be Announced?
SSA doesn’t guess, and it doesn’t publish early estimates, no matter how many financial newsletters try.
- The agency measures CPI-W data during the third quarter (July through September) of each year.
- The official announcement always comes in October, once the Bureau of Labor Statistics finalizes that quarter’s numbers.
- Independent analysts sometimes publish unofficial COLA projections earlier in the year based on inflation trends, but none of those carry SSA’s authority until October’s release.
- Set a reminder to check SSA’s site in October, or sign up for update alerts through your online account, rather than relying on speculative headlines in the spring.
How Do You Confirm Your Own COLA Notice and Plan Around It?
Don’t wait for a paper letter that might sit in your mailbox for weeks. Handle it directly:
- Log into or create a my Social Security account. Doing so before mid-November tends to give you earlier access to your notice in the Message Center.
- Check the Message Center specifically. That’s where your personalized COLA letter usually posts before the mailed version arrives.
- If your net increase looks smaller than expected, check your Medicare Part B premium against SSA’s FAQ page before assuming an error occurred.
- Update any recurring payments or auto-drafts tied to your benefit amount, and build in a short cash-flow buffer for the transition month.
- If your finances are complicated by taxes, multiple income sources, or Medicare surcharges, a trusted financial advisor can walk through the net numbers with you.
What the 2026 COLA Really Means for Your Long-Term Plan
It’s a preservation mechanism, not a growth engine, and healthcare costs in particular tend to outrun it. Retirees who treat Social Security as one leg of a broader income plan, rather than the whole structure, tend to weather these annual adjustments with far less anxiety.
— Josh
Where to Go Next If You Want to Protect More of Your Income
Social Security’s COLA keeps you roughly even with inflation. It doesn’t build wealth, and it was never meant to. Joshthinks exists for the part of the conversation that comes after the COLA notice: how to think about markets, policy, and stewardship in a way that actually helps you hold onto purchasing power over the long run.

If you’re trying to understand how market-based tools fit into a retirement income plan, our guide on what financial futures actually are breaks down the mechanics without the jargon. Curious how policy decisions ripple into your household budget? Our look at how futures exchanges shape prices connects those dots directly. And if you want a faith-grounded lens on money management alongside the policy analysis, our piece on Christian economics and stewardship is a natural next stop. Start with whichever topic matches where you’re stuck, and work from there.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.


