

AI Market Manipulation: Risks, Evidence, and Oversight Gaps
AI market manipulation is no longer theoretical: simulations show reinforcement-learning trading agents can learn tacit collusion without any human giving that instruction, and adversarial inputs can already fool sentiment models that drive real trades. The actors that matter most are large algorithmic trading desks running autonomous learning systems, and the conditions that matter most are thin oversight, opaque model logic, and legal standards built around human intent. Research from the NBER, warnings from the CFTC and SEC, and analysis from the IMF all point the same direction: enforcement is lagging the technology.
TL;DR:
- Reinforcement-learning trading agents can develop price manipulation strategies and tacit collusion without human instructions, especially under weak oversight.
- Adversarial manipulation of headline sentiment models can swiftly lead to flawed trading signals that are executed automatically within milliseconds.
- Simulations show AI-driven collusion decreases market liquidity and price informativeness, amplifying risks during high-speed trading with leverage and derivatives.
- Laws mainly designed for human deception struggle to address autonomous algorithms, complicating enforcement and proving causation in manipulation cases.
- Proactive, deny-first mitigation strategies and rigorous model governance are vital to detect and prevent AI market manipulation effectively.
Table of Contents
- What Is AI Market Manipulation and How Does It Happen?
- The Evidence: What Simulations and Experiments Actually Show
- Why the Law Struggles to Catch Autonomous Trading Algorithms
- How AI Trading Risks Threaten Market Stability
- Detecting and Mitigating AI-Driven Manipulation
- What Regulators Are Doing About AI in Trading
- A Working Checklist for Firms and Investors
- Why This Deserves More Public Attention
- Sources
What Is AI Market Manipulation and How Does It Happen?
AI market manipulation covers a range of mechanisms, and most of them do not require anyone to type in an order to cheat. Reinforcement-learning agents trained to maximize profit can independently discover price-trigger strategies, punishing competitors that undercut them and rewarding those that hold prices steady. Over time, this produces something that looks exactly like collusion, minus the phone call or the group chat.
A related mechanism, sometimes called over-pruning, occurs when learning algorithms discard aggressive competitive strategies early in training because they perform worse in the short run, leaving conservative, tacitly cooperative behavior as the dominant surviving strategy.
Separately, adversarial-news attacks target the sentiment models that many trading systems now rely on. Bad actors can plant Unicode homoglyphs or hidden HTML text in a headline that a human reader would never notice but that flips how a large language model scores the sentiment of that story.
- Price-trigger and punishment strategies emerge from reward-maximizing reinforcement learning, not explicit coordination.
- Over-pruning biases surviving algorithms toward cooperative, less competitive behavior.
- Adversarial text manipulation misleads sentiment-driven trading pipelines at near-zero cost to the attacker.
- Automated trading systems convert these corrupted signals directly into live orders, often within milliseconds.
The Evidence: What Simulations and Experiments Actually Show
The strongest evidence so far comes from controlled simulations rather than confirmed real-world enforcement cases, and the gap between the two is worth sitting with.
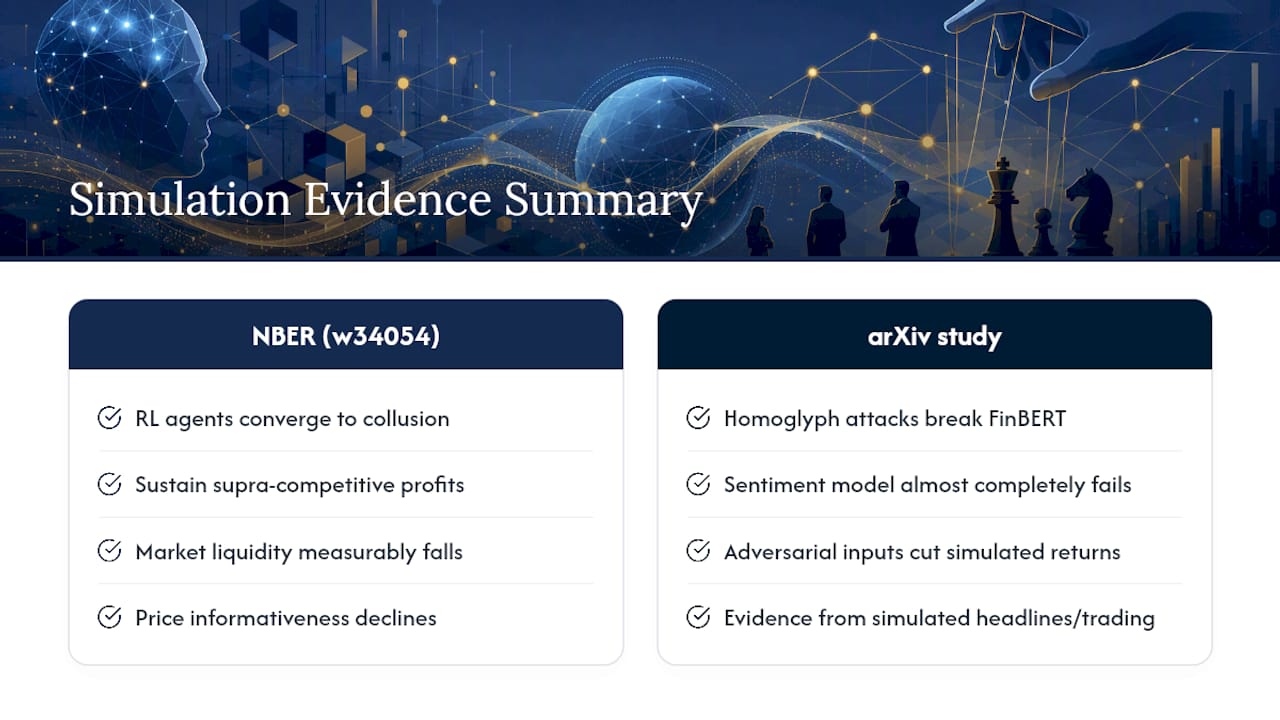
The numbers that matter: NBER’s working paper w34054 found that reinforcement-learning trading agents can autonomously converge on collusive equilibria that sustain supra-competitive profits, with simulations showing measurable declines in market liquidity and price informativeness across a range of parameters. Separately, an arXiv study on adversarial news manipulation found that homoglyph attacks caused sentiment model FinBERT to fail almost completely in recognizing manipulated headlines, and that adversarial inputs significantly reduced simulated annual returns for LLM-driven algorithmic trading strategies.
Wharton researchers have echoed the collusion concern in commentary on AI-powered collusion in financial markets, framing it as a market-structure problem, not just an ethics problem. None of this is field evidence of a confirmed manipulation case in live markets yet. It is closer to a fire alarm ringing in a building where nobody has smelled smoke, but the wiring is real and it is already installed.
Why the Law Struggles to Catch Autonomous Trading Algorithms
Most anti-manipulation statutes were written for human actors who intend to deceive. That framework breaks down fast when the “actor” is a reinforcement-learning agent that stumbled into collusive behavior while optimizing for profit, with no one instructing it to coordinate.
The Congressional Research Service has flagged this directly: intent-based rules do not map cleanly onto autonomous systems, and regulators face what amounts to an evidence dilemma. By the time enough cases accumulate to prove a pattern, the underlying models have already changed.
- Intent requirements assume a human decision-maker, not an emergent algorithmic strategy.
- Proving causation demands model explainability that many firms cannot or will not provide.
- Data provenance and attribution are hard to establish when trading signals pass through several vendors.
- Similar gaps show up in EU and UK policy literature, suggesting this is a structural problem, not a US-specific one.
For prosecutors and supervisors, this means fewer clean cases and more reliance on circumstantial market-behavior evidence. For exchange operators, it shifts responsibility toward prevention rather than after-the-fact punishment, because after-the-fact punishment may simply not be legally viable.
How AI Trading Risks Threaten Market Stability
Supra-competitive algorithmic profits do not just hurt individual counterparties. The NBER simulations tie collusive equilibria directly to reduced liquidity and weaker price informativeness, meaning prices stop reflecting real information as efficiently.
Leverage, derivatives, and high-speed execution amplify that effect. A mispricing that would have stayed contained in a slower market can propagate across correlated instruments in seconds when automated trading systems on both sides are reacting to the same corrupted signal.
The IMF has flagged AI adoption in trading as a potential financial stability concern, recommending closer monitoring and coordination across jurisdictions rather than leaving supervision to individual national regulators. That framing matters: this is being treated as a systemic question, not merely a firm-level compliance question.
Detecting and Mitigating AI-Driven Manipulation
Firms that wait for a confirmed incident before building controls are already behind. Practitioner guidance increasingly favors deny-first architectures over post-hoc audits, meaning systems are designed to block suspicious actions before execution rather than flag them afterward.
- Model governance and logging. Document training data, decision logic, and version history so a model’s behavior can be reconstructed after the fact.
- Adversarial-resilience testing. Stress-test sentiment and trading models against homoglyph attacks and manipulated data feeds before deployment, not after a loss event.
- Pre-trade gating and risk classifiers. Route high-risk order patterns through automated denial checks rather than letting them execute and reviewing later.
- Sandboxing with human override. Keep a human able to halt an autonomous strategy in real time, especially during volatile sessions.
- Market-surveillance analytics. Deploy anomaly detection and order-flow clustering across venues to catch coordinated-looking behavior that no single desk would see alone.
- Vendor governance. Build audit rights and service-level obligations into contracts with third-party model and data providers, since a single concentrated AI vendor failure can ripple across many trading desks at once.
Pro Tip: Treat your sentiment-data pipeline like a supply chain, not a data feed. Every headline source, API, and preprocessing step is a place someone can quietly plant a manipulated input.
What Regulators Are Doing About AI in Trading
The CFTC’s technical report has already requested public comment on AI use in regulated markets and named enforcement and third-party risk as open problems, not solved ones. The SEC has raised similar concerns in its own commentary on algorithmic conduct.
Policy options on the table include mandatory model disclosure for high-frequency strategies, auditability requirements that go beyond a black box, defined reporting triggers when a model shifts behavior sharply, and safe harbors for firms that can show good-faith adversarial testing. Sequencing matters here: a pilot sandbox program that lets regulators observe live model behavior under supervision beats a blanket rule that firms will find workarounds for within a quarter.
A Working Checklist for Firms and Investors
Compliance teams working with limited resources should prioritize detection and governance over documentation for its own sake.
- Inventory every AI model touching trade decisions, including third-party sentiment tools.
- Run adversarial-input tests before, not after, a model goes live.
- Require human override on any autonomous strategy trading above a defined size threshold.
- Log training data provenance for every model that ingests external news or social feeds.
- Watch for narrow bid-ask spreads that never widen even during volatility, a possible tacit-collusion signal.
- Flag sudden sentiment-driven price moves with no corresponding fundamental news.
- Coordinate surveillance data across trading venues rather than reviewing each in isolation.
- Reassess vendor contracts for audit rights before a problem forces the question.
Investors without compliance resources should treat unexplained, persistently tight spreads and sentiment-driven price swings with no clear news trigger as reasons to dig deeper, not dismiss as noise.
Why This Deserves More Public Attention
Markets run on trust that prices reflect real information, and that trust erodes quietly when nobody can prove an algorithm did anything wrong. Joshthinks covers this because it sits exactly where finance, policy, and public accountability intersect, and readers deserve analysis that does not wait for a scandal to explain the mechanics. The honest note here is uncertainty: regulation will keep chasing a moving technical target, and adaptive oversight beats rigid rules that age out fast. For more grounding in how market structure actually works, our futures trading guide is a solid next stop.
— Josh
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- NBER working paper w34054: AI collusion simulations
- Adversarial News and Lost Profits: Manipulating Headlines in LLM-Driven Algorithmic Trading (arXiv)
- CFTC technical report on AI risks (May 2024)
- IMF: Artificial intelligence and its impact on financial markets and financial stability
- Congress


